
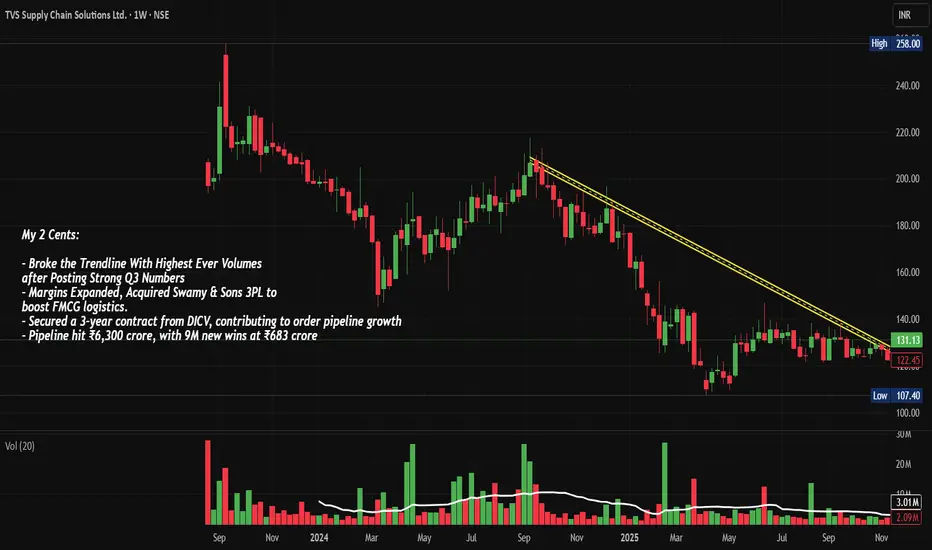
TVS Supply Chain Solutions Just Broke Out on 12x Volume After Hitting Rock Bottom; Technical Reversal Meets a ₹6,300 Crore Order Pipeline. This Breakout Could Define TVS Supply's Next 12 Months. Let's Understand in "Chart of the Week"
As per the Latest SEBI Mandate, this isn't a Trading/Investment RECOMMENDATION nor for Educational Purposes; it is just for Informational purposes only. The chart data used is 3 Months old, as Showing Live Chart Data is not allowed according to the New SEBI Mandate.
Disclaimer: "I am not a SEBI REGISTERED RESEARCH ANALYST AND INVESTMENT ADVISER."
This analysis is intended solely for informational purposes and should not be interpreted as financial advice. It is advisable to consult a qualified financial advisor or conduct thorough research before making investment decisions.
Price Action:
- The stock has experienced significant volatility over the past 18 months, declining approximately 49% from its peak of ₹258 in September 2023 to the current level
- Recent price action shows a dramatic reversal, with the stock surging on record volumes after hitting multi-year lows around ₹92-100 zone
Volume Spread Analysis:
- Exceptional volume spike visible in the latest session: 84.25 million shares traded versus 20-day average of 6.66 million
- This represents a volume explosion of approximately 12.6x the normal trading activity
- The volume surge accompanies the price breakout, indicating strong institutional participation and genuine buying interest
- Prior to this breakout, the stock exhibited consistently low volumes during the downtrend, suggesting capitulation and lack of seller interest at lower levels
Base Formation and Accumulation:
- The stock formed a classic accumulation base between September 2025 and February 2026, spanning approximately 5 months
- Base range: ₹92-140, with the stock consolidating primarily in the ₹100-125 zone
- This base represents a 60%+ correction from the all-time highs, suggesting significant value discovery
- The base formation shows Some characteristics of a rounding bottom pattern with decreasing volatility toward the end
- Smart money appears to have accumulated positions during the ₹100-115 range when retail sentiment was most negative
Key Support Levels:
- Immediate Support: ₹115-120 (recent breakout zone and prior resistance)
- Secondary Support: ₹105-110 (base midpoint and volume cluster)
- Strong Support: ₹92-100 (52-week low and multi-year support zone)
- Critical Support: ₹85 (psychological level; breach would invalidate bullish structure)
Key Resistance Levels:
- Immediate Resistance: ₹140-145 (previous swing high from October 2025)
- Major Resistance: ₹160-170 (200-day moving average zone and gap resistance)
- Psychological Resistance: ₹180-190 (quarterly pivot and volume resistance)
- Long-term Resistance: ₹220-230 (2024 swing high cluster)
- Ultimate Resistance: ₹258 (all-time high from September 2023)
Trend Structure:
- The stock has broken above multiple descending trendlines that had contained price action since September 2023
- The current breakout suggests potential channel exit and trend reversal
Fundamental and Sectoral Backdrop:
Company Overview:
- TVS Supply Chain Solutions is one of India's largest integrated supply chain solutions providers and part of the ₹8.5 billion TVS Group
- Operations span across two primary segments: Integrated Supply Chain Solutions (55% of revenue) and Network Solutions (including Global Forwarding Solutions and Integrated Final Mile Solutions)
- Global presence across 26 countries and 4 continents with 24.7 million sq. ft. of warehouse capacity (19.9 million sq. ft. in India)
- Serves over 91 Fortune 500 customers across automotive, industrial, consumer, technology, rail, utilities, and healthcare sectors
Recent Financial Performance:
- Q3 FY26 revenue grew 11.1% year-on-year to ₹2,715.8 crore
- EBITDA rose 36.7% to ₹205.8 crore, with margins expanding to 7.6% from 6.2%
- The company reported a consolidated net profit of ₹10.72 crore in Q3 December 2025 compared with a net loss of ₹24.65 crore in Q3 December 2024
- Excluding the impact of new wage code compliance costs, adjusted profit stood at ₹18.02 crore versus a loss of ₹23.80 crore in the prior year
- The company has a ₹6,300 crore order pipeline
Strategic Initiatives and Growth Catalysts:
- Strategic acquisition of Swamy & Sons 3PL for ₹88 crore to strengthen FMCG logistics capabilities
- Swamy & Sons has deep domain expertise in FMCG logistics with a strong presence in Andhra Pradesh and Telangana
- The acquisition brings 116 warehouses across 5 states totaling approximately 4 million sq. ft., with over 70% of revenue from FMCG players
- Recent contract wins include a 3-year contract from DICV (Daimler India Commercial Vehicles) for in-plant warehouse management
- New CEO Vikas Chadha appointed effective January 22, 2026, bringing fresh leadership perspective
Sectoral Outlook: Indian Logistics Industry:
- India's logistics sector is valued at approximately $243.8 billion in 2025 and projected to reach $429.0 billion by 2034
- The sector is well-positioned for strong growth with an expected CAGR of 10.7% till 2026
- Logistics costs have dipped below 10% of GDP for the first time, down from 13-14%
- Union Budget 2026-27 allocates ₹5,98,520 crore to the transport sector with initiatives including new Dedicated Freight Corridors and 20 National Waterways
Government Policy Support:
- PM Gati Shakti National Master Plan has integrated 57 Central Ministries and 36 states with 1,700 data layers for unified infrastructure planning
- National Logistics Policy aims to reduce logistics costs from 13-14% of GDP to 8% by 2030
- 35 key locations approved for Multi-Modal Logistics Parks development, with 5 expected to be operational by 2027
- Indian e-commerce is expected to grow at a CAGR of 27% to reach $163 billion by 2026, driving demand for efficient last-mile delivery services
Industry Tailwinds:
- Rise of third-party logistics with the India 3PL market forecast to increase by $16.77 billion at a 9.45% CAGR between 2023 and 2028
- E-commerce volumes surged to $380 billion in 2025, with AI adoption tripling among SMEs for predictive routing
- Manufacturing push under Make in India and PLI schemes increasing demand for integrated supply chain solutions
- Dedicated Freight Corridors hit 96% operational status, improving rail connectivity
Competitive Position and Concerns:
- TVS SCS has positioned itself among the top warehousing 3PL service providers in India post Swamy & Sons acquisition
- The company's digital capabilities leveraging AI, IoT, and Machine Learning provide competitive advantages
- However, the company has faced challenges including high valuation multiples, weak capital efficiency, and ongoing regulatory disputes
- Five-year sales growth of 8.64% is considered modest for a growing sector
- Stock has significantly underperformed both the Sensex and the transport services sector over the past 1-2 years
Technical Summary:
- The stock has completed a multi-month base formation and broken out on exceptional volumes, suggesting institutional accumulation
- The breakout from the descending channel indicates a possible trend reversal
- Critical resistance zones exist at ₹140-145, ₹160-170, and ₹180-190 that will determine the sustainability of this move
- Volume confirmation is the strongest technical positive, with 12.6x average volume supporting the breakout
Fundamental Summary:
- The company has achieved a profitability turnaround, with Q3 FY26 showing margin expansion and return to profit after previous quarter losses
- Strategic acquisition of Swamy & Sons strengthens FMCG logistics capabilities, a high-growth segment within supply chain
- A robust order pipeline of ₹6,300 crore provides revenue visibility for coming quarters
- The Indian logistics sector is entering a golden period with government support, infrastructure development, and e-commerce growth creating strong tailwinds
Critical Factors to Monitor:
- Ability to sustain above ₹115-120 support zone in near term
- Follow-through buying in coming sessions to confirm breakout validity
- Quarterly execution and margin trajectory in FY26 Q4 and FY27
- Integration success of Swamy & Sons acquisition and synergy realization
- Broader market conditions and risk appetite for mid-cap stocks
- Progress on the ₹6,300 crore order pipeline conversion to revenue
My 2 Cents:
- The technical setup suggests this could be a pivotal moment for TVS Supply Chain, with the potential for a sustained upward move if the breakout holds
- The combination of technical reversal patterns, record volume, and improving fundamentals creates a compelling near-term setup
- However, investors should remain cautious about the multiple overhead resistance levels and the stock's history of failed rallies
- The sectoral tailwinds from government infrastructure spending and e-commerce growth provide a supportive macro backdrop
- Risk management through appropriate stop-losses below ₹115 is essential given the stock's high volatility
Full Coverage on my Mid-Week Newsletter coming Wednesday.
Keep in the Watchlist and DOYR.
NO RECO. For Buy/Sell.
📌Thank you for exploring my idea! I hope you found it valuable.
🙏FOLLOW for more
👍BOOST if you found it useful.
✍️COMMENT below with your views.
Meanwhile, check out my other stock ideas on the right side until this trade is activated. I would love your feedback.
As per the Latest SEBI Mandate, this isn't a Trading/Investment RECOMMENDATION nor for Educational Purposes; it is just for Informational purposes only. The chart data used is 3 Months old, as Showing Live Chart Data is not allowed according to the New SEBI Mandate.
Disclaimer: "I am not a SEBI REGISTERED RESEARCH ANALYST AND INVESTMENT ADVISER."
This analysis is intended solely for informational purposes and should not be interpreted as financial advice. It is advisable to consult a qualified financial advisor or conduct thorough research before making investment decisions.
As per the Latest SEBI Mandate, this isn't a Trading/Investment RECOMMENDATION nor for Educational Purposes; it is just for Informational purposes only. The chart data used is 3 Months old, as Showing Live Chart Data is not allowed according to the New SEBI Mandate.
Disclaimer: "I am not a SEBI REGISTERED RESEARCH ANALYST AND INVESTMENT ADVISER."
This analysis is intended solely for informational purposes and should not be interpreted as financial advice. It is advisable to consult a qualified financial advisor or conduct thorough research before making investment decisions.
Price Action:
- The stock has experienced significant volatility over the past 18 months, declining approximately 49% from its peak of ₹258 in September 2023 to the current level
- Recent price action shows a dramatic reversal, with the stock surging on record volumes after hitting multi-year lows around ₹92-100 zone
Volume Spread Analysis:
- Exceptional volume spike visible in the latest session: 84.25 million shares traded versus 20-day average of 6.66 million
- This represents a volume explosion of approximately 12.6x the normal trading activity
- The volume surge accompanies the price breakout, indicating strong institutional participation and genuine buying interest
- Prior to this breakout, the stock exhibited consistently low volumes during the downtrend, suggesting capitulation and lack of seller interest at lower levels
Base Formation and Accumulation:
- The stock formed a classic accumulation base between September 2025 and February 2026, spanning approximately 5 months
- Base range: ₹92-140, with the stock consolidating primarily in the ₹100-125 zone
- This base represents a 60%+ correction from the all-time highs, suggesting significant value discovery
- The base formation shows Some characteristics of a rounding bottom pattern with decreasing volatility toward the end
- Smart money appears to have accumulated positions during the ₹100-115 range when retail sentiment was most negative
Key Support Levels:
- Immediate Support: ₹115-120 (recent breakout zone and prior resistance)
- Secondary Support: ₹105-110 (base midpoint and volume cluster)
- Strong Support: ₹92-100 (52-week low and multi-year support zone)
- Critical Support: ₹85 (psychological level; breach would invalidate bullish structure)
Key Resistance Levels:
- Immediate Resistance: ₹140-145 (previous swing high from October 2025)
- Major Resistance: ₹160-170 (200-day moving average zone and gap resistance)
- Psychological Resistance: ₹180-190 (quarterly pivot and volume resistance)
- Long-term Resistance: ₹220-230 (2024 swing high cluster)
- Ultimate Resistance: ₹258 (all-time high from September 2023)
Trend Structure:
- The stock has broken above multiple descending trendlines that had contained price action since September 2023
- The current breakout suggests potential channel exit and trend reversal
Fundamental and Sectoral Backdrop:
Company Overview:
- TVS Supply Chain Solutions is one of India's largest integrated supply chain solutions providers and part of the ₹8.5 billion TVS Group
- Operations span across two primary segments: Integrated Supply Chain Solutions (55% of revenue) and Network Solutions (including Global Forwarding Solutions and Integrated Final Mile Solutions)
- Global presence across 26 countries and 4 continents with 24.7 million sq. ft. of warehouse capacity (19.9 million sq. ft. in India)
- Serves over 91 Fortune 500 customers across automotive, industrial, consumer, technology, rail, utilities, and healthcare sectors
Recent Financial Performance:
- Q3 FY26 revenue grew 11.1% year-on-year to ₹2,715.8 crore
- EBITDA rose 36.7% to ₹205.8 crore, with margins expanding to 7.6% from 6.2%
- The company reported a consolidated net profit of ₹10.72 crore in Q3 December 2025 compared with a net loss of ₹24.65 crore in Q3 December 2024
- Excluding the impact of new wage code compliance costs, adjusted profit stood at ₹18.02 crore versus a loss of ₹23.80 crore in the prior year
- The company has a ₹6,300 crore order pipeline
Strategic Initiatives and Growth Catalysts:
- Strategic acquisition of Swamy & Sons 3PL for ₹88 crore to strengthen FMCG logistics capabilities
- Swamy & Sons has deep domain expertise in FMCG logistics with a strong presence in Andhra Pradesh and Telangana
- The acquisition brings 116 warehouses across 5 states totaling approximately 4 million sq. ft., with over 70% of revenue from FMCG players
- Recent contract wins include a 3-year contract from DICV (Daimler India Commercial Vehicles) for in-plant warehouse management
- New CEO Vikas Chadha appointed effective January 22, 2026, bringing fresh leadership perspective
Sectoral Outlook: Indian Logistics Industry:
- India's logistics sector is valued at approximately $243.8 billion in 2025 and projected to reach $429.0 billion by 2034
- The sector is well-positioned for strong growth with an expected CAGR of 10.7% till 2026
- Logistics costs have dipped below 10% of GDP for the first time, down from 13-14%
- Union Budget 2026-27 allocates ₹5,98,520 crore to the transport sector with initiatives including new Dedicated Freight Corridors and 20 National Waterways
Government Policy Support:
- PM Gati Shakti National Master Plan has integrated 57 Central Ministries and 36 states with 1,700 data layers for unified infrastructure planning
- National Logistics Policy aims to reduce logistics costs from 13-14% of GDP to 8% by 2030
- 35 key locations approved for Multi-Modal Logistics Parks development, with 5 expected to be operational by 2027
- Indian e-commerce is expected to grow at a CAGR of 27% to reach $163 billion by 2026, driving demand for efficient last-mile delivery services
Industry Tailwinds:
- Rise of third-party logistics with the India 3PL market forecast to increase by $16.77 billion at a 9.45% CAGR between 2023 and 2028
- E-commerce volumes surged to $380 billion in 2025, with AI adoption tripling among SMEs for predictive routing
- Manufacturing push under Make in India and PLI schemes increasing demand for integrated supply chain solutions
- Dedicated Freight Corridors hit 96% operational status, improving rail connectivity
Competitive Position and Concerns:
- TVS SCS has positioned itself among the top warehousing 3PL service providers in India post Swamy & Sons acquisition
- The company's digital capabilities leveraging AI, IoT, and Machine Learning provide competitive advantages
- However, the company has faced challenges including high valuation multiples, weak capital efficiency, and ongoing regulatory disputes
- Five-year sales growth of 8.64% is considered modest for a growing sector
- Stock has significantly underperformed both the Sensex and the transport services sector over the past 1-2 years
Technical Summary:
- The stock has completed a multi-month base formation and broken out on exceptional volumes, suggesting institutional accumulation
- The breakout from the descending channel indicates a possible trend reversal
- Critical resistance zones exist at ₹140-145, ₹160-170, and ₹180-190 that will determine the sustainability of this move
- Volume confirmation is the strongest technical positive, with 12.6x average volume supporting the breakout
Fundamental Summary:
- The company has achieved a profitability turnaround, with Q3 FY26 showing margin expansion and return to profit after previous quarter losses
- Strategic acquisition of Swamy & Sons strengthens FMCG logistics capabilities, a high-growth segment within supply chain
- A robust order pipeline of ₹6,300 crore provides revenue visibility for coming quarters
- The Indian logistics sector is entering a golden period with government support, infrastructure development, and e-commerce growth creating strong tailwinds
Critical Factors to Monitor:
- Ability to sustain above ₹115-120 support zone in near term
- Follow-through buying in coming sessions to confirm breakout validity
- Quarterly execution and margin trajectory in FY26 Q4 and FY27
- Integration success of Swamy & Sons acquisition and synergy realization
- Broader market conditions and risk appetite for mid-cap stocks
- Progress on the ₹6,300 crore order pipeline conversion to revenue
My 2 Cents:
- The technical setup suggests this could be a pivotal moment for TVS Supply Chain, with the potential for a sustained upward move if the breakout holds
- The combination of technical reversal patterns, record volume, and improving fundamentals creates a compelling near-term setup
- However, investors should remain cautious about the multiple overhead resistance levels and the stock's history of failed rallies
- The sectoral tailwinds from government infrastructure spending and e-commerce growth provide a supportive macro backdrop
- Risk management through appropriate stop-losses below ₹115 is essential given the stock's high volatility
Full Coverage on my Mid-Week Newsletter coming Wednesday.
Keep in the Watchlist and DOYR.
NO RECO. For Buy/Sell.
📌Thank you for exploring my idea! I hope you found it valuable.
🙏FOLLOW for more
👍BOOST if you found it useful.
✍️COMMENT below with your views.
Meanwhile, check out my other stock ideas on the right side until this trade is activated. I would love your feedback.
As per the Latest SEBI Mandate, this isn't a Trading/Investment RECOMMENDATION nor for Educational Purposes; it is just for Informational purposes only. The chart data used is 3 Months old, as Showing Live Chart Data is not allowed according to the New SEBI Mandate.
Disclaimer: "I am not a SEBI REGISTERED RESEARCH ANALYST AND INVESTMENT ADVISER."
This analysis is intended solely for informational purposes and should not be interpreted as financial advice. It is advisable to consult a qualified financial advisor or conduct thorough research before making investment decisions.

Related publications
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.
Related publications
Disclaimer
The information and publications are not meant to be, and do not constitute, financial, investment, trading, or other types of advice or recommendations supplied or endorsed by TradingView. Read more in the Terms of Use.