Multi-Anchor VWAP Grid [AGPro Series]Multi-Anchor VWAP Grid
🔹 Overview
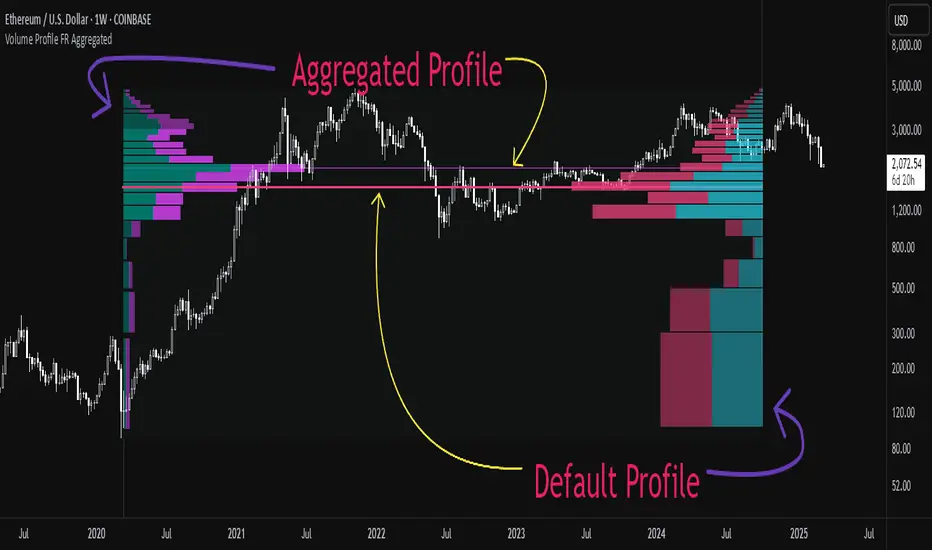
Multi-Anchor VWAP Grid is a volume-weighted analysis tool that plots five independently anchored VWAP lines on the same chart — anchored from swing high, swing low, higher-timeframe pivot, all-time high, and session open. Each anchored VWAP includes optional ±1σ and ±2σ standard deviation bands, forming a dynamic grid of volume-weighted support and resistance levels. When three or more VWAPs converge within a tight ATR-based band, the indicator draws a rectangular confluence zone highlighting the area as a higher-probability price reaction region.
The script is fully automatic. All five anchors are detected by internal engines (pivot detection, session detection, timeframe change detection, all-time-high tracker) and require no manual date picking or retroactive anchor placement. Install the indicator, select which anchors you want active, and the grid builds itself.
🔹 What It Does Differently
Most anchored VWAP tools plot one anchor at a time and require the user to manually place the anchor each time a new swing or event is identified. This script plots five anchors simultaneously and lets them compete for relevance. When multiple independent anchors agree on a price level, that agreement itself becomes the signal — visualized as a confluence zone. A single VWAP is one data point. Five VWAPs intersecting within 0.5 ATR of each other is a structural event.
The confluence detection engine tests each active VWAP as a reference point, counts how many others fall within the user-defined ATR tolerance, and picks the densest cluster on each bar. A minimum VWAP count threshold (default 3) prevents noise, and a lifecycle manager extends, adaptively resizes, and expires zones based on bar age and midpoint drift.
🔹 Methodology
**Anchor engines**
Swing High and Swing Low VWAPs reset on each confirmed pivot using the standard ta.pivothigh / ta.pivotlow detector with a configurable lookback length. HTF Pivot VWAP resets at the start of each selected higher-timeframe period (daily, weekly, or monthly) using timeframe.change. ATH VWAP resets whenever a new all-time high is printed on the visible chart. Session Open VWAP resets at the first bar of each trading session defined by the session window input.
**VWAP calculation**
Each anchor maintains three running accumulators since its last reset: sum of (price × volume), sum of volume, and sum of (price² × volume). VWAP is computed as the first divided by the second. Standard deviation is derived from the variance identity: sqrt(E − E ²), where E and E are computed from the running accumulators. Bands are plotted at configurable multipliers of this running standard deviation.
**Confluence engine**
On each bar, the script evaluates every active VWAP as a potential cluster center. For each candidate center, it counts how many other active VWAPs fall within ATR × tolerance distance. The cluster with the highest count wins. If the winning count meets or exceeds the minimum threshold, the bar is marked as confluence-active.
**Zone lifecycle**
When confluence becomes active, a new rectangular zone is created spanning the min/max of the clustered VWAPs. As long as confluence remains active and the cluster midpoint drifts less than 0.5 ATR from its original midpoint, the zone extends to the current bar and adaptively resizes with rate-limited expansion (maximum 1 ATR growth per bar per direction, preventing erratic stretching). If the midpoint drifts more than 0.5 ATR, a new zone is created. A 5-bar debounce prevents micro-breaks in confluence from prematurely closing active zones. Zones auto-expire after a configurable age limit (default 120 bars).
🔹 Signals and Panel Readouts
The information panel in the top-right corner (position and theme configurable) displays:
- **Price Bias** — count of VWAPs price is currently above vs below, with an overall BULL / BEAR / MIXED classification
- **Confluence** — current status (active with cluster count, or none) and the minimum-count threshold in use
- **Closest VWAP** — which of the five VWAPs is currently closest to price, and the distance in ATR units
- **Active VWAPs** — each enabled VWAP's current value and percent distance from close
Two alert conditions are built in: new confluence zone detection, and price crossing any active VWAP line.
🔹 Key Inputs
**Anchor Points group** — toggle each of the five VWAPs on or off, set swing pivot lookback length, choose HTF timeframe (D/W/M), define the session window for intraday anchoring.
**Deviation Bands group** — toggle bands on or off, configure band 1 and band 2 multipliers, enable or disable gradient fills between VWAP and the first band.
**Confluence Zones group** — toggle zones on or off, set minimum VWAPs required for a confluence (2 to 5), adjust the ATR-based tolerance, define maximum zone age in bars.
**Panel group** — toggle panel, choose location (six positions), select Dark or Light theme, set font size (Small / Normal / Large).
**Labels group** — toggle the compact end-of-line labels that identify each VWAP at the right edge of the chart.
🔹 How to Use
This indicator is designed as a context layer, not a standalone entry signal. Suggested workflow:
**1. Identify structural bias.** Check the Price Bias row in the panel. If 4 or 5 VWAPs sit below price (BULL), the market is trading above its most relevant volume-weighted averages across multiple timeframes and event contexts. The opposite applies for BEAR.
**2. Watch for confluence formation.** When the panel shows Confluence ACTIVE with 3 or more VWAPs clustered, a meaningful volume-weighted support or resistance area is forming. These zones often precede reaction or reversal behavior.
**3. Use bands for context.** When price trades near the ±1σ band of a single VWAP, reversion back toward that VWAP is statistically more likely. ±2σ extensions indicate volatility outliers.
**4. Cross-reference with your own tools.** This script is most useful combined with price action, volume profile, or a trend filter of your choice. It does not generate entries or exits on its own.
🔹 Tips
- On crypto 24h markets, set Session Window to 0000-2359 for a full-day session VWAP.
- Higher Swing Pivot Length values (30–50) filter noise on higher timeframes; lower values (10–15) are better for intraday.
- If the chart feels visually crowded, disable the ±2σ bands or reduce the number of active anchors. All five are rarely needed simultaneously.
- For the strongest confluence signals, increase Min VWAPs for Confluence to 4 — rarer but higher conviction.
🔹 Limitations and Transparency
- The script uses standard Pine Script pivot detection for swing anchors. Pivots are confirmed only after the pivot length has passed, which means swing VWAP anchors are placed retrospectively by that many bars. This is an inherent limitation of all pivot-based tools, not a bug.
- ATH tracking is limited to the visible chart range. On timeframes or symbols where the chart does not load full history, the "ATH" anchor represents the highest point within loaded data, not the true all-time high.
- Standard deviation bands assume price dispersion around each VWAP is approximately normal over the anchored period. In strongly trending markets, this assumption weakens and bands may widen significantly.
- Confluence zones are descriptive, not predictive. They mark areas where multiple volume-weighted averages happen to agree. They do not guarantee price reaction, only indicate where reaction is more plausible than average.
- Session Window input must match the instrument's trading hours to produce a meaningful intraday VWAP. Incorrect session definitions will produce misleading anchor points.
🔹 Risk Disclosure
This indicator is provided for educational and analytical purposes only. It is not financial advice, investment advice, or a recommendation to buy, sell, or hold any asset. All trading involves substantial risk of loss. Past chart behavior and historical VWAP reactions do not guarantee future results. Users are solely responsible for their own trading decisions and risk management. Always combine indicator output with independent analysis and appropriate position sizing. The author accepts no responsibility for any financial outcome resulting from the use of this script. Indicator

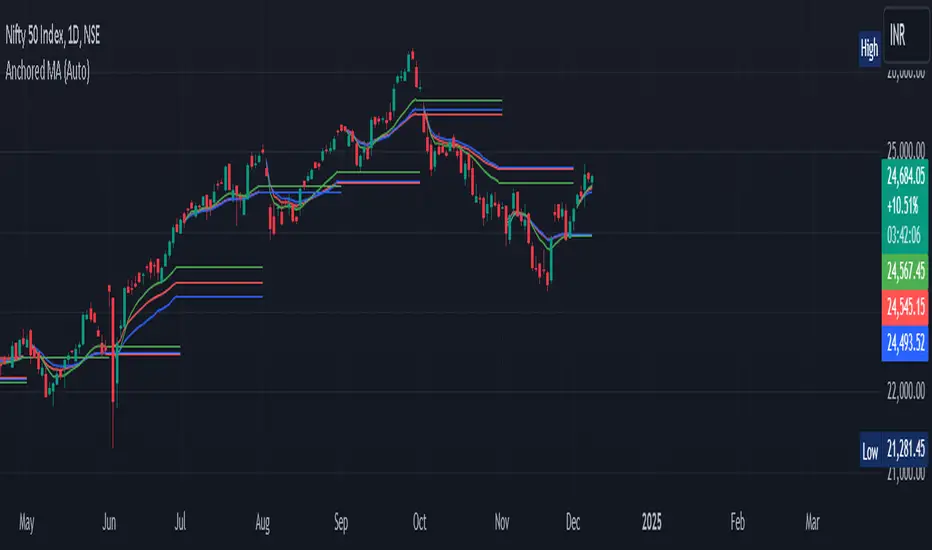
AG Pro Anchored VWAP Event Map [AGPro Series]AG Pro Anchored VWAP Event Map
Overview / What it does
AG Pro Anchored VWAP Event Map is an overlay built to organize price action around Anchored VWAP after a meaningful starting point has been defined. Instead of treating VWAP as a single static reference, this script focuses on the relationship between price and a chosen anchor, then maps how the market behaves after that anchor is established. The goal is not to forecast price, but to make post-anchor structure easier to read in a consistent visual framework.
The script supports three anchor paths: Open, Swing, and Event. Open mode can reset the anchor from a daily, weekly, or monthly opening context. Swing mode rebuilds the anchor from a confirmed pivot high or pivot low. Event mode is designed for expansion-type situations and can anchor from a range expansion, a volume spike, or a breakout impulse. This creates a flexible workflow for traders who want to study how price responds to AVWAP under different structural conditions without switching tools.
Once the anchor is set, the script plots the Anchored VWAP, builds a distance band around it, tracks reclaim and reject behavior, and summarizes the current post-anchor bias in a compact panel. The result is a clean event map that can be used to study acceptance, rejection, recovery, or continuation around an anchored reference level. It is meant to simplify interpretation, not replace market context.
A key design goal of this script is clarity. The visual package is intentionally structured so the anchor, AVWAP path, distance zone, signal labels, and bias panel can be read together without turning the chart into a dense signal board. In practice, that means the indicator is most useful when it is treated as a contextual decision-support tool rather than a standalone trigger engine.
Unique Edge
The main distinction of this script is that it is not built as a generic VWAP overlay. Its emphasis is on post-anchor behavior. That means the visual logic starts from the selected anchor event and then evaluates how price interacts with the anchored VWAP afterward. In other words, the anchor is not only a starting point for the line itself; it is the center of the script's interpretation model.
Another differentiator is the combination of multiple anchor sources within one workflow. Traders can use opening-session logic, confirmed swing logic, or event-driven logic depending on the type of market behavior they are studying. This makes the indicator suitable for different styles of chart review while keeping the interface straightforward.
The distance band adds a second layer of structure. Rather than reading only the AVWAP line, users can also see whether price is operating close to the reference, stretched around it, or reacting from the upper or lower band zone. This helps frame whether a move appears to be re-accepting the anchored average, rejecting away from it, or trading in a more extended state.
The script also tries to keep the signal layer readable through selective label logic. Reclaim and reject markers are not intended to flood the chart. They are there to mark notable interactions with the anchored framework, while the panel provides a compact summary of the active anchor, current bias, distance, and latest signal state.
Methodology
The script begins by defining an anchor source. In Open mode, the anchor can be tied to a daily, weekly, or monthly opening transition. In Swing mode, the script waits for a confirmed pivot high or pivot low based on the selected swing length. In Event mode, the anchor is created only when a qualifying market event appears according to the selected event model.
For event-based anchoring, the script can use one of three internal conditions. Range Expansion looks for directional range behavior relative to ATR and recent structure. Volume Spike looks for directional participation with higher-than-average volume and a meaningful candle body fraction. Breakout Impulse looks for directional movement through recent extremes with supportive range and volume characteristics. These are practical anchor candidates for traders who want the AVWAP to begin from a meaningful change in behavior rather than from a calendar reset.
After the anchor is created, the script calculates Anchored VWAP using cumulative price-volume data relative to that anchor point. From there, it builds a distance band around the AVWAP. The band can be defined by ATR or percentage mode, depending on whether the user prefers a volatility-based or proportional framework.
Post-anchor bias is then derived from a simple internal score. The script evaluates whether price is above or below AVWAP, whether the AVWAP slope is improving or weakening, and whether price is trading beyond the distance band. This produces a practical Bullish, Bearish, or Neutral state. The intention is not to compress market structure into a perfect score, but to provide a compact directional read that can be used alongside the chart.
Reclaim and reject logic is based on how price interacts with the AVWAP and the surrounding band after the anchor is active. A reclaim highlights price moving back through the anchored reference with confirmation, while a reject highlights failure or pushback behavior around the band area. These events are intended as structural observations rather than guaranteed trade setups.
Signals & Alerts
The script includes reclaim and reject signal logic for both directions. These labels are designed to call attention to notable interactions with the anchored framework after the selected anchor becomes active. In practical use, reclaim behavior can be interpreted as a sign that price is attempting to re-establish acceptance relative to AVWAP, while reject behavior can suggest rejection away from the mapped zone.
Because market structure can become noisy, the script also includes signal spacing and density controls to reduce repetitive label clutter. This is especially relevant when anchored conditions remain active for long periods and price repeatedly tests the same area. The goal is to preserve readability while still marking relevant interactions.
Alert conditions are included for bullish reclaim, bearish reclaim, bullish reject, bearish reject, and a broader any-signal state. These alerts are deterministic within the script's ruleset, but they should still be used as workflow tools rather than interpreted as self-sufficient trading instructions.
Key Inputs
Anchor Source:
Choose whether the indicator should anchor from Open, Swing, or Event logic.
Open Anchor Type:
In Open mode, select daily, weekly, or monthly opening context.
Swing Length:
Controls how confirmed pivot highs and lows are detected in Swing mode.
Event Type:
In Event mode, choose between Range Expansion, Volume Spike, or Breakout Impulse as the anchor trigger model.
Event Lookback / Multipliers / Cooldown:
These inputs control how strict the event selection becomes and how frequently new event anchors can appear.
Band Mode:
Switch between ATR-based and percentage-based distance bands.
ATR Band Multiplier / Percent Band:
Define the width of the distance zone around Anchored VWAP.
Signal Density:
Helps regulate how aggressively reclaim and reject labels are displayed.
Panel and Label Size:
Allows the visual layout to remain readable across different chart styles and screen sizes.
Show Anchor Label / Show Anchor Level / Show Bias Ribbon:
These toggles control the visibility of anchor-focused visual elements and optional bias coloring.
Limitations & Transparency
This script is an interpretation aid. It does not identify the single correct anchor for all market environments. Different anchor choices can lead to different AVWAP paths, different reclaim or reject readings, and different conclusions. That is normal, and it is one of the reasons the script provides multiple anchor modes.
Event-based anchors depend on internal threshold logic such as ATR expansion, volume conditions, and breakout behavior. On some symbols or timeframes, those filters may trigger more frequently or less frequently than expected. Users may need to adjust event sensitivity and band settings to fit the market they are analyzing.
Reclaim and reject states are rule-based. They are not a guarantee of continuation, reversal, or follow-through. In sideways conditions, repeated AVWAP interactions can occur without producing a sustained directional move. The script can help organize those interactions visually, but it cannot remove market uncertainty.
The post-anchor bias is intentionally simplified. It is designed for readability, not for complete market classification. It should be read together with broader price structure, higher-timeframe context, liquidity conditions, and user-defined execution rules.
Risk Disclosure
This indicator is for chart analysis and workflow support. It does not provide financial advice, investment advice, or guaranteed outcomes. Markets involve risk, and any trading or investing decision remains the sole responsibility of the user.
No indicator can remove uncertainty from live markets. Anchored VWAP, reclaim behavior, reject behavior, and bias states are analytical references only. They should be validated with independent judgment, risk management, and broader market context before being used in any decision-making process.
Use this script as a structured visualization tool, not as a promise of performance or a substitute for disciplined trade planning.
Indicator

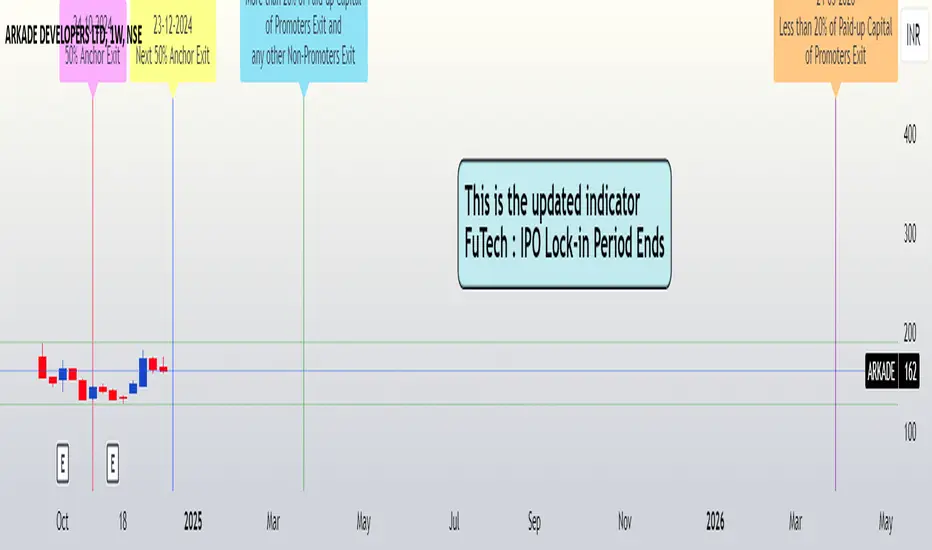
FuTech : IPO Lock-in Ends FuTech: Lock-in Ends - First ever unique Indicator on the TradingView platform
Hello Everyone !
Introducing the first-ever unique indicator on the TradingView platform to track the lock-in period expiry dates for IPOs.
The FuTech Lock-in Ends Indicator is specifically designed to assist traders and investors in identifying the key dates when lock-in periods for IPO shares come to an end.
This provides an edge in preparing for potential market movements driven by buying or selling pressures associated with significant share volumes.
=============================================================
Key Features:
1. Tracks Multiple Lock-in Periods:
- Identifies dates when the 30 days, 90 days, 6 months, and 18 months lock-in periods for IPO shares expire.
- Helps traders anticipate potential market action driven by share releases.
2. IPO Lock-in Ends dates as per Compliance with SEBI Guidelines:
- SEBI (Securities and Exchange Board of India) mandates lock-in periods for IPO shares based on investor categories:
- A) Promoters:
- Lock-in period reduced to 18 months for up to 20% of post-issue paid-up capital (previously 3 years).
- For shareholding exceeding 20%, the lock-in period is further reduced to 6 months (previously 1 year).
- B) Anchor Investors:
- 50% of allotted shares: Lock-in period of 90 days from the date of allotment.
- Remaining 50% of shares: Lock-in period of 30 days from the date of allotment.
- C) Non-promoters:
- Lock-in period reduced to 6 months (previously 1 year).
After these lock-in periods end, investors may buy / sell their shares, which can result in significant market activity.
3. Visual Indicator on Charts:
- The indicator draws vertical lines on the TradingView chart at the respective lock-in expiry dates.
- Alerts users in advance about potential market activity due to the release of locked shares.
- Traders can use these alerts to prepare for positions or adjust their existing holdings accordingly.
4. Customizable Settings:
- Users can modify the color of the labels and width of the lines to suit their preferences and enhance chart visibility.
5. User-defined Allotment Dates:
- If the allotment date is known, users can input this information directly. The indicator will then calculate the lock-in period dates based on the provided allotment date, ensuring precise results.
- If no allotment date is entered, the default calculation assumes the allotment date to be three trading days prior to the listing date .
=============================================================
Important Notes:
- Allotment Date Calculation:
- In the absence of user-defined allotment dates, the indicator estimates the allotment date as three trading days prior to the listing date .
- This approximation may deviate by one to two days from the actual event for certain IPOs.
- Proactive Alerts:
- Most dates are intentionally marked 1-2 days in advance to give traders sufficient time to act, whether for taking new positions or squaring off existing ones to avoid unfavorable losses.
=============================================================
The FuTech Lock-in Ends Indicator is a must-have tool for IPO traders and investors looking to stay ahead of market movements. Use it to track key dates and plan your trading strategy effectively with FuTech : Chart is Art.
=============================================================
Thank you !
Jai Swaminarayan Dasna Das !
He Hari ! Bas Ek Tu Raji Tha ! Indicator

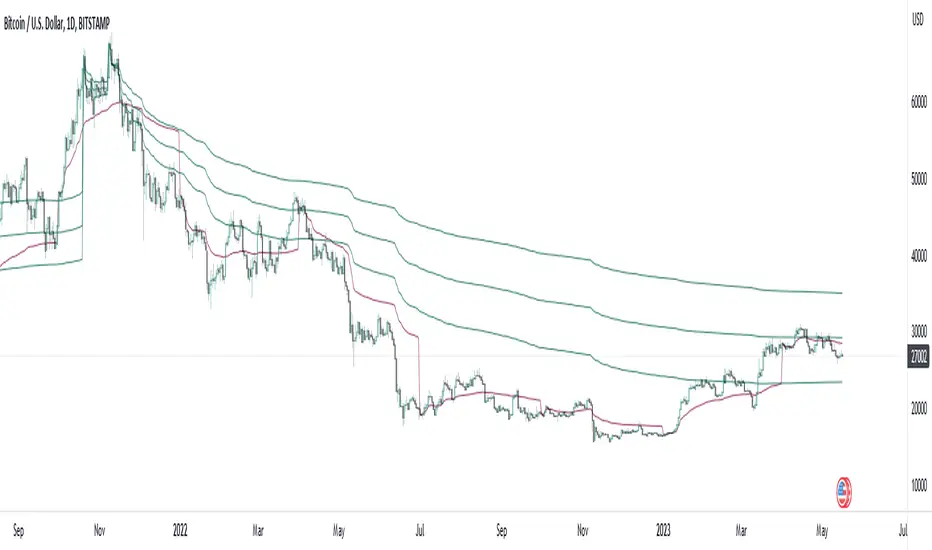
VWAP RangeThe VWAP Range indicator is a highly versatile and innovative tool designed with trading signals for trading the supply and demand within consolidation ranges.
What's a VWAP?
A VWAP (Volume Weighted Average Price) represents an equilibrium point in the market, balancing supply and demand over a specified period. Unlike simple moving averages, VWAP gives more weight to periods with higher volume. This is crucial because large volumes indicate significant trading activity, often by institutional traders, whose actions can reflect deeper market insights or create substantial market movements. The VWAP is also often used as a benchmark to evaluate the efficiency of executed trades. If a trader buys below the VWAP and sells above it, they are generally considered to have transacted favourably.
This is how it works:
Multiple VWAP Anchors:
This indicator uses multiple VWAPs anchored to different optional time periods, such as Daily, Weekly, Monthly, as well as to the highest high a lowest low within those periods. This multiplicity allows for a comprehensive view of the market’s average price based on volume and price, tailored to different trading styles and strategies.
Dynamic and Fixed Periods:
Traders can choose between using dynamic ranges, which reset at the start of each selected period, and specifying a date and time for a particular fixed range to trade. This flexibility is crucial for analyzing price movements within specific ranges or market phases.
Fixed ranges allow VWAPs to be calculated and anchored to a significant market event, the beginning of a consolidation phase or after a major news announcement.
Signal Generation:
The indicator generates buy and sell signals based on the relationship of the price to the VWAPs. It also allows for setting a maximum number of signals in one direction to avoid overtrading or pyramiding. Be sure to wait for the candle close before trading on the signals.
Average Buy/Sell Signal Lines:
Lines can be plotted to display the average buy and sell signal prices. The difference between the lines shows the average profit per trade when trading on the signals in that range. It's a good way to see how profitable a range is on average without backtesting the signals. The lines will also often turn into support and resistance areas, similar to value areas in a volume profile.
Customizable Settings:
Traders have control over various settings, such as the VWAP calculation method and bar color. There are also tooltips for every function.
Hidden Feature:
There's a subtle feature in this indicator: if you have 'Indicator values' turned on in TradingView, you'll see a Sell/Buy Ratio displayed only in the status line. This ratio indicates whether there are more sell signals than buy signals in a range, regardless of the Max Signals setting. A red value above 1 suggests that the market is trending upward, indicating you might want to hold your long positions a bit longer. Conversely, a green value below 1 implies a downward trend.
Indicator

Indicator

Indicator

Indicator