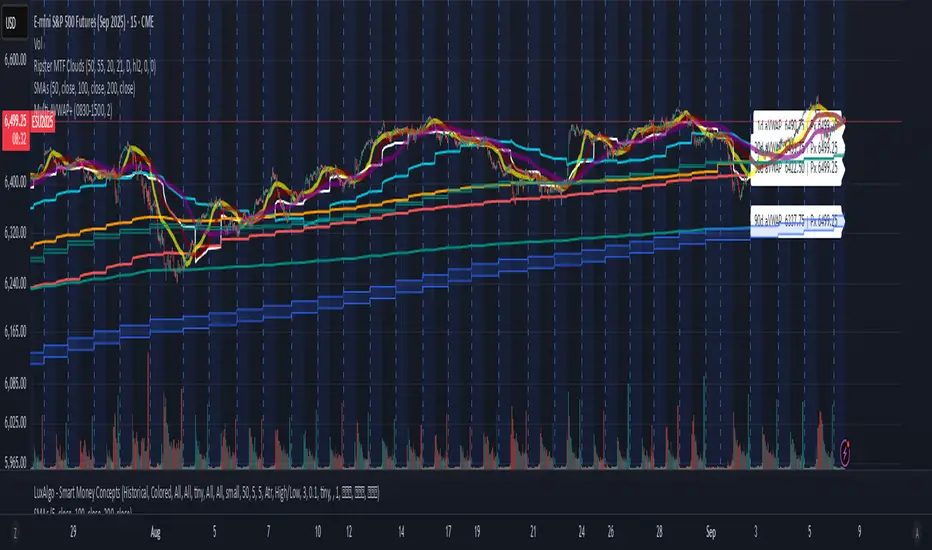
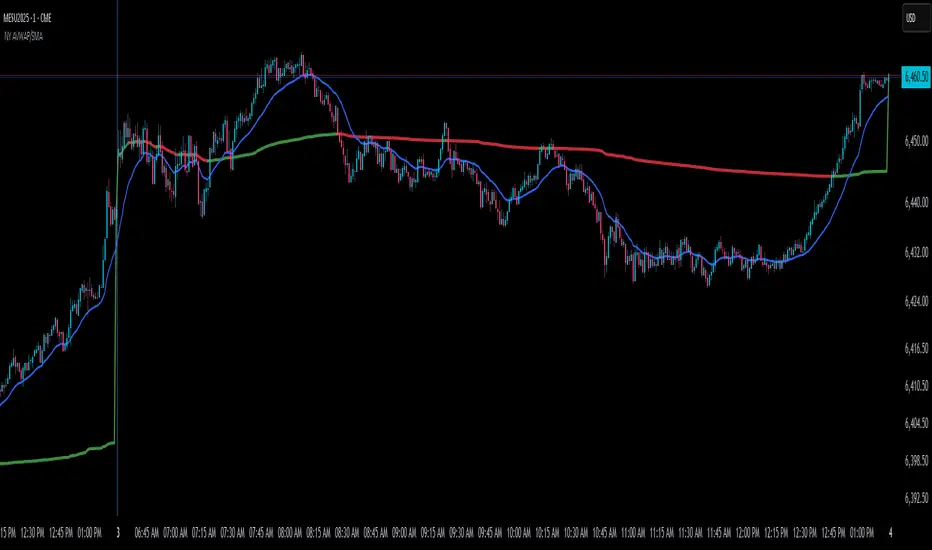
VWAP A BE BOPVWAP A BE BOP — Every Anchor You'll Ever Need, One Indicator
VWAP A BE BOP consolidates the anchored VWAP toolkit that traders normally piece together from three or four separate scripts into a single, clean overlay. Instead of hunting for daily VWAP here, a weekly anchor there, and a rolling previous-day reference somewhere else, every timeframe you actually trade around lives in one place — fully customizable, fully synced.
Five calendar-anchored VWAPs — Daily, Weekly, Monthly, Quarterly, and Yearly — give you the institutional reference levels that price consistently reacts to, each with its own toggle and color so you can build exactly the confluence stack your strategy calls for. Layer a fast Daily VWAP against a slower Monthly or Quarterly anchor to instantly see whether you're trading with or against the higher-timeframe flow.
Daily and Previous Day deviation bands bring statistical context to the mix. Three independently adjustable standard-deviation multipliers (defaulting to 1, 2, and 2.5) mark the zones where price has statistically stretched from fair value — classic mean-reversion and breakout-confirmation territory, without cluttering your chart with bands on every single line.
A true Previous Day VWAP, anchored precisely at session open with zero configuration required, plus optional rolling lines going back a full week — perfect for spotting how current price stacks up against where the market was trading 2, 3, or even 7 sessions ago.
Fully adjustable labels turn a wall of colored lines into an instantly readable chart. Rename any line to whatever shorthand you like — "pDay," "M," "Q" — and control label size and horizontal offset so the tags sit exactly where you want them, whether you're on a widescreen monitor or a cramped mobile chart.
Built for traders who live and die by mean reversion, fair value, and institutional order flow, VWAP A BE BOP strips away the noise of over-engineered multi-panel scripts and gives you a single, elegant, endlessly configurable VWAP suite — the last VWAP indicator you'll need to add to your chart.
For educational and informational purposes only. Not financial advice. Indicator

VWAP Suite [vault]VWAP Suite
Most traders treat VWAP like a single line. This tool treats it the way Auction Market Theory treats it: as a developing value area with a center, an upper edge and a lower edge, tracked across every timeframe that matters, with the previous period frozen next to the current one so you always know where price sits relative to value.
Everything is inside one indicator. Session VWAPs from daily to yearly, standard deviation bands that form the value area, previous period levels, right side labels for every higher timeframe level, and rolling VWAPs over 7, 30, 90 and 365 days.
WHAT IT PLOTS
1. Session VWAPs (Daily, Weekly, Monthly, Quarterly, Yearly)
Each period has its own anchored VWAP that resets at the start of the period. The reset follows the exchange session of the symbol, not midnight UTC, so on CME futures a new daily VWAP starts at 18:00 New York, on OANDA gold at 17:00 New York, and so on. Weekly, monthly, quarterly and yearly resets follow the same logic.
You can enable any combination of these, each with its own color. By default the VWAP lines are drawn dotted so they do not compete visually with the bands and rolling lines. A "Dotted VWAP Lines" toggle switches them back to solid.
The lines break at the period change instead of drawing a vertical jump to the new starting level, so every session or week or month shows as its own clean block.
2. Standard Deviation Bands (Value Area)
Pick one period under "Anchored to Period" and the indicator draws its standard deviation bands around that VWAP:
- VWAP plus 1 SD = VAH (value area high)
- VWAP minus 1 SD = VAL (value area low)
- optional plus and minus 2 SD outer bands
The area between VAH and VAL is filled. Fill transparency is adjustable and defaults to a very subtle 95 so the band reads as a shadow behind price rather than a colored block.
The deviation is calculated with volume weighting from the same cumulative data as the VWAP itself, so VAH and VAL are the true volume weighted 1 SD edges of the developing value area. Bands also break at the period change.
3. Previous Period Levels
At the start of every new period the indicator freezes the VWAP and standard deviation of the period that just closed. Those frozen values are carried forward as flat lines through the current period:
- previous VWAP
- previous VAH and VAL (plus and minus 1 SD)
- optional previous plus and minus 2 SD
These are the levels that matter most from an Auction Market Theory point of view. Price opening inside the previous value area, above it, or below it tells you what kind of day or week you are likely dealing with. The previous value area can be filled as well, with a separate "Fill Prev Bands" toggle.
Each of the five periods keeps its own frozen values, so the previous weekly VAH is genuinely the VAH of last week, not of the last day.
4. HTF Labels (Weekly, Monthly, Quarterly, Yearly)
This is the part that keeps the chart clean. Instead of plotting eight or ten extra lines you get labels on the right side of the chart for the higher timeframe levels:
- current VWAP, VAH, VAL for each of W, M, Q, Y
- previous VWAP, VAH, VAL for each of W, M, Q, Y
Every single label has its own checkbox, so you can show exactly the ones you use and nothing else. Each period has its own color, and previous period labels are automatically dimmed so you can tell them apart at a glance. Two group switches, "Show Current Labels" and "Show Previous Labels", turn whole sets on and off.
Each label comes with a short horizontal tick line drawn at the price level, so you can see where the level sits even when the line itself is not plotted.
5. Rolling VWAPs (7, 30, 90, 365 day)
Rolling VWAPs do not reset. They always look back a fixed number of days and give you the volume weighted average of that whole window. They are calculated by time, not by bar count, so a 30 day rolling VWAP is the same 30 days whether you are on a 5 minute chart or a 4 hour chart. Each one has its own toggle, color and label.
Note on history: the 365 day line needs roughly a year of bars on your chart. On low timeframes with limited history it will be calculated from the first available bar. It is off by default for that reason.
LABEL CONTROLS
- Label Offset: how many bars to the right of the current bar the labels sit
- Label Size: tiny, small, normal or large
- Label Tick Length: length of the short line drawn in front of each label
- Show Right-Side Labels: one master switch that hides every label on the right in one click. Lines and fills stay. Useful when you want to screenshot a clean chart or when the labels start stacking up during a tight range.
HOW WE USE IT
The core idea is that VWAP is fair value for the period and the 1 SD bands are the edges of value. Price accepted inside the bands is balance. Price outside the bands is either an imbalance that will be faded back to value or the start of a trend that leaves the old value area behind.
A few things to watch for:
- Price opening the day or week outside the previous value area and holding there. That is acceptance away from old value and usually the start of a directional move.
- Price opening outside the previous value area and coming straight back inside. Failed breakout, look for a rotation to the other side of the value area.
- Daily VAH or VAL lining up with a weekly or monthly VWAP or value area edge. Stacked value edges from multiple timeframes are where the strongest reactions happen.
- Rolling 7D and 30D crossing or converging. That is medium term value shifting and it often precedes a larger move on the session timeframes.
The labels on the right are there so you never have to guess which level a line represents or scroll around to find the monthly VWAP.
CALCULATION NOTES
- Source is hlc3 by default and can be changed.
- VWAP is the volume weighted average of the source since the period start. Standard deviation is the volume weighted deviation of the source around that VWAP.
- Session boundaries come from the symbol's own exchange calendar.
- On symbols without volume (some CFDs and spot pairs), the indicator falls back to equal weighting so it still plots a time weighted average and bands rather than nothing.
- No repainting. Every value is computed from closed data and a period's frozen levels never change once the period has ended.
- Written in Pine Script v6.
INPUTS OVERVIEW
General: source, label offset, label size, label tick length, right side labels master switch
Session VWAPs: Daily / Weekly / Monthly / Quarterly / Yearly with colors, line width, dotted or solid
Standard Deviation Bands: on/off, anchored period, fill on/off, 2 SD bands on/off, colors, fill transparency
Previous Period Levels: prev 1 SD levels, prev 2 SD levels, prev labels, fill prev bands, color
HTF Labels: current / previous group switches, then per period color and six individual checkboxes (VWAP, VAH, VAL, pVWAP, pVAH, pVAL)
Rolling VWAPs: 7 / 30 / 90 / 365 day with colors
Works on any market and any timeframe. Built for futures and gold on intraday charts but the logic is the same on crypto, forex and stocks. Indicator

Swing Anchored VWAP Deviation [Pineify]Swing Anchored VWAP Deviation
Overview
Swing Anchored VWAP Deviation maps volume-weighted equilibrium after a swing. Its line, field, marker, and dashboard encode origin, dispersion, zone, and volume status.
Problem Definition
Session VWAP resets by time even when the boundary is unrelated to a contextual swing. Manual anchors require hindsight; naive pivot automation can reset on small zigzags or imply knowledge before confirmation. Fixed-width bands also equate distances across tight and dispersed auctions. The invariant needed is a confirmed anchor, statistics beginning at the real swing without an early signal, and distance scaled by post-anchor volume.
Design Rationale
Confirmed left/right pivots provide structural origins. ATR-scaled distance from the latest opposing pivot filters small candidates; zero disables the gate. After acceptance, a finite replay covers pivot through confirmation, retaining the real statistical origin while delaying visible state until it is knowable. Online weighted moments reduce cancellation versus squared-price sums. Backward plots were rejected as misleading, and reset bars cannot trigger crosses caused only by the new frame.
Key Features
Confirmed swing anchors with an ATR prominence gate.
Online volume-weighted mean, variance, and nested bands.
Stable zone colors with optional markers, bar colors, wash, and dashboard.
Close-confirmed crosses and outer entries that ignore reset bars.
How It Works
HLC3 is the default source. On each closed bar, pivots use left/right windows. Distance from the latest opposing pivot is divided by ATR at the pivot bar; if both types confirm, the larger score wins.
Acceptance clears state and processes pivot through confirmation in order. Valid volume weights each sample. Online updates produce total weight, mean, and second moment; deviation is the square root of moment divided by weight. Later bars extend state once. Missing volume has zero weight, with no fallback.
Bands are AVWAP plus or minus selected deviation multiples. Close-to-AVWAP distance divided by deviation supplies sigma; a one-tick floor prevents zero division. Cyan/blue means positive deviation, orange/pink negative, and gray equilibrium. Low anchors are cyan and highs amber. Markers are placed on the swing after confirmation; bands start or jump at confirmation and never backfill.
How Multiple Indicators Work Together
This is one causal chain, not unrelated signals. Pivot confirmation defines origin; the ATR gate decides replacement; volume weights define equilibrium; weighted variance normalizes distance; and zone state drives visuals and alerts. Without confirmation there is hindsight ambiguity, without the gate there is reset noise, without volume equilibrium changes meaning, and without dispersion raw distances are incomparable.
Trading Ideas and Insights
Treat AVWAP as context for post-swing acceptance or rejection, not an entry command. Sustained closes on one side show where value is forming. An outer visit is large relative to volume-weighted dispersion, but does not choose continuation over mean reversion. Compare it with structure, liquidity, and holding period. Alerts are observation prompts, not orders or performance claims.
Unique Aspects
The contribution is confirmation-to-origin replay. Common automation either starts at the later confirmation bar or draws pivot history where the pivot was unknowable. This state includes genuine pivot-to-confirmation observations, yet changes visuals and alerts only after confirmation. Online weighted moments keep center and dispersion together; the opposing-swing gate limits trivial resets; reset suppression separates price movement from a changed frame.
How to Use
Begin with liquid stocks, futures, or crypto on roughly 15-minute to daily charts. Require Volume Weight ACTIVE in the dashboard. Read AVWAP as current equilibrium, the inner field as ordinary variation, and outer fields as larger normalized displacement. H or L marks the source swing but appears only after the right window completes. Configure each cross and outer-entry alert separately.
Customization
Left and Right Bars set swing scale and confirmation delay; larger values usually mean fewer, later anchors. Minimum Opposing Swing Distance filters in ATR units: raising it extends anchor life, while zero accepts all candidates. Source selects the weighted sample. Inner choices are 0.5, 1.0, and 1.5; outer choices are 2.0, 2.5, and 3.0. Field, markers, extreme wash, bar colors, and dashboard are independent switches, leaving AVWAP readable alone.
Assumptions and Limitations
Pivots arrive after Right Bars; marker location is not discovery time. The realtime bar can change AVWAP, variance, bands, colors, and dashboard, while anchors and alerts require a close. Volume must be reliable: absent, synthetic, delayed, or inconsistent data can remove output or distort the center. Results are path- and parameter-dependent because each anchor replaces the prior distribution. ATR gating can miss small turns or admit noisy large ones. Deviation is descriptive, not a probability guarantee, especially for skewed data. The script does not infer orders, profitability, or future price.
Conclusion
This indicator connects confirmed structure with volume-weighted distance while keeping timing auditable. Statistics originate at the swing, become visible only after confirmation, and expose volume, latency, reset, and realtime limits.
Indicator

Auction & Liquidity Command Center Volume Profile, MeasuredAuction & Liquidity Command Center — Volume Profile, Measured
The levels traders already use — prior POC, value area, naked POCs, prior day high/low, session AVWAP, HVN/LVN — each scored by its measured reaction on this chart: how often price rejects vs breaks, and what the fade has been worth in R. Levels with evidence, not levels with vibes. Never a buy or sell.
What it does
Every structure tool draws levels. None of them measures what happens when price gets there. This tool builds the session-anchored auction map with profile-grade accuracy, detects qualified touches of every level, resolves each touch through a triple-barrier outcome, and pools the results by level TYPE into a live scoreboard: pPOC +0.01R · rej 50% · n156. You see not just where the levels are, but which kinds of levels have actually meant something on this chart — and which are coin flips.
The components, and why they are combined
This is a deliberate synthesis of four parts, each covering the previous one's weakness:
A profile-grade level engine (Market Profile — J. P. Steidlmayer). Nine level types from the session volume-at-price profile and session extremes: prior POC, prior VAH/VAL (classical two-row 70% expansion), naked POCs (prior POCs never revisited), prior day high/low, the session's anchored VWAP, and HVN/LVN volume nodes (prominence-filtered local extremes). Accuracy choices: each bar's volume is distributed range-proportionally across the rows it overlaps (not binned at one point); POC ties break toward the session center. Weakness left open: a drawn level says nothing about whether it matters.
A qualified-touch detector. A level must be ARMED — price fully away from it by at least k×ATR — before a touch of it can count, and it disarms after every touch. Chop sitting on a line cannot enter the record. Approach direction is stored with every event. Weakness left open: a touch is not an outcome.
Triple-barrier outcome resolution (outcome labelling — M. López de Prado). From each touch: REJECT if price moves m×ATR back the way it came first, BREAK if it moves m×ATR through first, TIMEOUT after T bars. Purity rules: barriers are fixed at the ATR of the touch moment; evaluation starts the bar after the touch; a bar hitting both barriers is a timeout, never a guess. Weakness left open: one level's history is n = 1.
Per-TYPE pooling with honesty gates. Statistics pool by level type, never by individual line — a type is a real sample. A type shows no score until a minimum number of its touches have resolved (default 20); until then it reads BUILDING with its count. Timeouts are reported in n but excluded from the reject/break ratio. Fade expectancy = (rejects − breaks) / (rejects + breaks), in R.
How to read it
Rails are colored and styled by type (solid profile levels, dashed day levels, dotted volume nodes, violet naked POCs); each label carries its type's live score or its BUILDING count.
Evidence on the chart: a gray • at every qualified touch, then ○ (teal) where the touch rejected and ✕ (amber) where it broke. Every number on the scoreboard can be audited against the chart.
Dashboard: nearest level and its score, with a plain-language verdict (tends to hold / coin flip / tends to break) so the read needs no statistics background; per-type scoreboard (fade R · reject % · n) for all nine types; touch counts; the exact engine settings in the NOTE row.
Honest expectations: most types on most charts score near zero — that is the truthful baseline, and seeing it protects you from folklore. The value is in the exceptions this chart's own history reveals (for example, day extremes often carry a modest positive fade expectancy while POC retests are a coin flip), and in knowing the difference.
How to use it
Use the scoreboard to weight your own playbook: give more respect to touches of types that have measured well here, less to types that grade as noise — and size accordingly. The "Touch of a MEASURED level" alert fires only when price reaches a type with a real sample behind it. This is context about where price reactions have had structure — never a direction, never an entry signal.
Non-repaint & universality
Profiles, POC/VA/nodes and day levels commit only at session close on confirmed bars; touches and outcomes resolve on confirmed bars; the AVWAP is cumulative within its session. Nothing repaints. The script requests no external data of any kind — no lower timeframes, no security calls — so it runs identically on every plan and every symbol with volume.
Use on any market
Volume source, profile rows, value-area %, node thresholds, arm distance, barriers and sample gates are all inputs. Defaults suit liquid intraday index futures; intraday timeframes give the engine the most touches to learn from.
Originality & credits
The synthesis — a range-proportional session profile, qualified-touch detection, touch-time-ATR triple-barrier outcomes, and per-type pooled reaction statistics displayed as a live scoreboard — is original work for this publication. Concept credits: Market Profile / point of control / value area — J. Peter Steidlmayer; naked (virgin) POC — market-profile literature; anchored VWAP — as popularised in modern trading literature; triple-barrier outcome labelling — M. López de Prado. Implementation and charting design are the author's own.
Disclaimer
Research and education only. NOT financial advice, NOT a signal service, NOT a guarantee of future results. Reaction statistics are empirical frequencies from this chart's limited history, pooled per level type; they change with regime and sample, and a positive expectancy is not a promise. Validate independently and manage your own risk. Indicator

Adaptive Volumetric Reversion Channel Fade ValidatorAdaptive Volumetric Reversion Channel — Fade Validator (AVRC)
What it is
AVRC is an anchored, volume-weighted regression channel that frames mean-reversion ("fade") setups and then gates, scores and validates them — so you can see whether fading stretched price actually has an edge on your symbol and timeframe instead of taking it on faith. It is a study / analysis framework, not a strategy and not a signal service.
Why these components are combined (the mashup rationale)
Fading an extreme asks three different questions, and no single classic tool answers all three. AVRC coordinates several non-redundant lenses on one shared geometry (an anchored regression channel) and one shared volatility unit (residual σ), so each lens can check the others rather than echoing it:
WHERE is price stretched? A volume-weighted regression centerline with residual-σ bands is drawn against a slower macro trend-relative volume map — volume binned by σ-distance from a longer regression line. Whether the tactical band sits in a thin (fast-traversed) or thick (heavily-traded) macro node tells you if a fade is likely clean or absorbed. This cross-read is the connective tissue between the two layers.
Is a reversion ACTUALLY firing? Independent "tells" at the band — a close-back rejection, a band-confluent momentum divergence, an equal-high/low liquidity sweep, and the macro-density read. Because these tells are correlated, their agreement is shrunk by a design-effect correction so echoes can't masquerade as independent confirmation.
Is the market in a reverting STATE? A regime gate (variance-ratio test + a reversion-trust correlation) only passes fades when price increments offset rather than compound. An entry-time ride-risk score (macro-trend alignment, the two-centerline spread, an already-walking band, momentum, mean-reversion half-life, and multi-timeframe trend consensus) flags fades likely to be "walked" rather than reverted.
The components share one geometry and one volatility unit, and each can veto the others. The goal is to suppress low-quality fades more than to generate them.
How the validation layer works (what makes this more than a drawing)
Every fade is logged and, a fixed horizon later, resolved: its forward return is measured in ATR units and tabulated Gate ON vs Gate OFF — follow-through %, a Wilson 95% interval, whipsaw %, and mean R per fade. Outcomes are additionally split Reverted vs Rode, by macro node (thin/thick), and by ride-risk (low/high at the running median). The panel's Edge line synthesizes this into a single read: is Gate ON's follow-through interval clearing the ungated baseline with positive mean R and enough samples? Per-fade rows also export to the Data Window for your own analysis. Every filter has to earn its place against the ungated baseline.
How to use it
Set the Price source (top of settings). Defaults are tuned for an intraday index future; the source is user-selectable so the framework runs on any symbol or market. Volume-based parts (heatmap, profile, POC) need a real volume feed.
Read the panel top-down: Now (live setup) → State (regime + spread + compression) → the A/B scoreboard (Gate OFF, Gate ON, Revert, Ride) → Edge verdict.
A fade arms when price tags the outer band and at least one tell prints, then passes only if the regime (and optional ride-risk) gate agrees. Target is the centerline or the nearest untested POC.
If Gate ON does not beat Gate OFF on follow-through and mean R with non-overlapping intervals and enough samples, the edge isn't there on this symbol/timeframe — change them, don't force it. The signal is clearest on higher intraday timeframes; 1-minute is mostly noise.
What is original here
The original work is the coordination: a shared-σ, timeframe-adaptive regression channel used as a reversion frame; a trend-relative volume map cross-read against the band; decorrelated tells fused by a design-effect shrink; a statistical regime gate; an entry-time ride-risk score; and a built-in A/B + forward-return validation harness — combined so each lens can veto the others and the tool reports its own hit rate. It is not a re-skin of any single indicator.
Concept credits (techniques are standard; this implementation is original)
Volume-weighted least-squares & polynomial regression; residual-σ channels; anchored VWAP (all standard); Volume Profile / Value Area / Point of Control — Market Profile (Steidlmayer / CBOT); Variance-Ratio test — Lo & MacKinlay (1988); design effect / effective sample size — Kish (1965); proportion confidence interval — Wilson (1927); mean-reversion half-life — Ornstein–Uhlenbeck process; ATR, RSI, Parabolic SAR — Wilder; Stochastic — Lane; Supertrend (classic, MTF context). Builds on established open-source regression-channel and anchored-VWAP techniques.
Settings (all defaults are on; tuned for an intraday index future)
Data/Source · Volatility unit · Macro volume heatmap · Tactical channel & bands · Interrelation & band-walk · Ride-risk filter · Density cross-read · Reversion tells · Regime gate · POC targets · Fade signal · Validation & export · Dashboard & theme (auto light/dark) · MTF trend context. The two signal-suppression gates (walk-gate, ride-gate) ship off so the indicator shows its signals and lets the validation panel tell you whether enabling them helps.
Disclaimer
For research and education only. NOT financial advice, NOT a recommendation, and NOT a guarantee of future results. All statistics shown are in-sample on loaded history, close-to-close at the horizon, without costs or slippage — a study aid, not a backtest. Mean reversion fails in trends and during regime breaks. Do your own research and manage your own risk. Indicator

Anchored VWAP Reversion ChannelAnchored VWAP Reversion Channel — Regime-Gated Fade Framework
## What this script does
This is an **analytical study** that frames mean-reversion ("fade") setups around an **anchored, volume-weighted regression channel**, then **gates** those setups by a statistical market-state test and **scores** them against their own forward outcomes. It does not place orders and it is not a signal service — its purpose is to let you see, on your own instrument and timeframe, whether fading a stretched move actually has an edge, instead of assuming it does.
It plots one channel (a centre line plus inner/outer residual-σ bands), marks fade setups at the outer band, draws supporting context (volume-profile POC / value area, untested prior-session POCs, momentum divergences, liquidity sweeps, and multi-timeframe trend lines), and reports a compact validation panel.
## Why these components are combined (mashup rationale)
Fading an extreme is really three separate questions, and no single classic indicator answers all three. Stacking look-alike indicators just echoes one input, so this tool deliberately combines **three non-redundant lenses and makes them check each other**:
1. **WHERE is price stretched?** — A **volume-weighted polynomial regression** anchored at the most recent swing pivot, with **residual-σ bands**. Because the curve tilts with the active leg, an outer-band tag stays meaningful even inside a trend, where a flat cumulative VWAP would not. A **volume profile** anchored to the *same* window supplies POC and value area, and prior-session POCs that have never since been traded through become **reversion targets**.
2. **Is a reversion actually firing here?** — Three orthogonal **tells** evaluated only at the band: a **close-back rejection**, a **band-confluent momentum divergence**, and an **equal-high/low liquidity sweep** (stop-run). Crucially, all three are derived from the same stretch, so their agreement is shrunk by a **design-effect correction** (effective-sample-size): three correlated echoes are not allowed to masquerade as three independent confirmations.
3. **Is the market in a reverting state at all?** — A **regime gate** combining a **variance-ratio test** and a **reversion-trust correlation** only lets a fade through when recent increments are offsetting (mean-reverting) rather than compounding (trending).
The pieces are not bolted together side by side: they share **one geometry** (the anchored channel) and **one volatility unit** (residual σ / ATR), and each can veto the others. A band tag with no tell does nothing; a tell with no reverting regime does nothing. The design goal is to **suppress** low-quality fades — into a trend, mid-range, or backed by a single echoed tell — more than to generate them.
## The honesty layer (what makes this more than a drawing)
Every fade that fires is logged and, a fixed horizon later, **resolved**: its forward return is measured in ATR units and tabulated **with the regime gate ON versus OFF**, reporting follow-through %, whipsaw %, a Wilson 95% confidence interval, and the **mean return per fade**. A per-fade series also exports to the Data Window so you can study the full return distribution offline. The gate has to **beat its own ungated baseline** to justify itself — the framework is built to be tested, not trusted blindly.
## How to use it
1. Set the **Price source** (group 01). It works on any symbol and any market; volume-based parts need a real volume feed.
2. A fade **arms** when price tags the outer band **and** at least one tell prints, then **passes** only if the regime gate reports a reverting state. Solid triangles are gated fades; the target is the centre line or the nearest untested POC.
3. Read the panel top-down: does **Gate ON** beat **Gate OFF** on both follow-through and mean R, with non-overlapping intervals and a reasonable sample size? If not, the edge is not present on this symbol/timeframe — change them rather than forcing the trade.
4. The signal lives on **higher intraday timeframes**; one-minute data is mostly noise.
## Defaults
Shipped tuned for **NSE:NIFTY** index futures on intraday timeframes (sources, pivot lengths, value-area %, and the Tuesday-style weekly session context reflect that instrument). Every value is exposed as an input — change the **Price source** and the relevant lengths to run the framework on any other instrument or market.
## What is original
The original work is the **coordination**, not any single formula: an anchored polynomial-regression channel used as a reversion frame, three decorrelated band tells fused by a design-effect shrink, a statistical regime gate, and a built-in A/B + forward-return validation harness — combined so each lens can veto the others and the whole thing reports its own hit rate. It is not a re-skin of one indicator.
## Concept credits (techniques are standard; this implementation is original)
Anchored VWAP (standard); volume-weighted least-squares / polynomial regression (standard); residual-σ channel (standard); Volume Profile, Value Area and POC — Market Profile, Steidlmayer / CBOT; Variance-Ratio test — Lo & MacKinlay (1988); design effect / effective sample size — Kish (1965); proportion confidence interval — Wilson (1927); ATR trailing stop / Supertrend (classic, used for the multi-timeframe context lines); RSI — Wilder; Stochastic — Lane.
## Disclaimer
For research and education only. This is an analytical study, **not** financial advice, **not** a recommendation, and **not** a guarantee of future results. All statistics shown are **in-sample** on loaded history, close-to-close, without costs or slippage — a study aid, not a backtest. Mean reversion fails in trends and through regime breaks. Do your own research and manage your own risk.
Indicator

Indicator

Anchored VWAP ChannelAnchored VWAP Channel — Regime, Confluence & Reversals
What it is
This is a single overlay that builds a complete read of price around one Anchored VWAP. Instead of just drawing a VWAP line, it wraps the VWAP in a volatility channel and then layers the context a discretionary trader normally checks by eye — where price sits versus fair value, whether the move is trending or stretched, where high-volume and Fibonacci levels line up, and where the edges are getting rejected. Everything is derived from the same anchor and measured in the same volatility unit (one standard deviation, σ), so the pieces describe one structure rather than competing with each other.
It runs on any asset class and any timeframe. On instruments that carry real volume (stocks, futures, crypto, etc.) the VWAP, the channel, and the volume profile are fully volume-weighted; on feeds without real volume it falls back gracefully and flags the change in the table (see "Notes and limitations").
Why these components are combined (and how they work together)
This is intentionally a mashup, and the parts are chosen because they answer different questions about the same reference point:
• The Anchored VWAP is the fair-value anchor — the volume-weighted average price since a chosen pivot.
• The channel turns dispersion around that anchor into a measurable unit: the bands are the AVWAP ± k·σ, where σ is the volume-weighted standard deviation of price about the VWAP. This converts "how far is price from fair value" into a number (σ-distance) every other module can reuse.
• The regime read uses that σ-distance together with the VWAP slope and the band behaviour to label continuation vs reversal — so the same channel that draws the bands also tells you whether to trust a band tag or fade it.
• The volume profile (Point of Control + Value Area) is computed over the same anchored window, so the high-volume price and the value range are measured on exactly the data the VWAP is built from — not an arbitrary separate lookback.
• The Fibonacci grid is drawn on the active swing leg and is only emphasised where a level coincides with the VWAP, a band, or the POC. The channel and profile are what make a fib level meaningful here; on their own the fib levels would be just lines.
• The reversal signals fire on outer-band rejections, and the optional confluence filter suppresses them while the regime is strongly trending (when band tags tend to continue) — i.e. one module gates another.
In short: the channel produces a σ-distance, and the regime, profile, fib confluence, reversal logic, divergence and squeeze modules all consume that single shared measurement. That shared plumbing is the reason these are bundled into one script instead of run as six separate indicators.
What it plots
• Anchored VWAP centerline with a glow halo, colored by slope direction.
• Channel bands at ±1σ and ±2σ. The fill can be a "reversion heat" gradient (denser toward the outer band, red above the VWAP, green below) or a neutral glow, or off.
• Volume profile drawn as a translucent Value Area box (VAL→VAH) with a distinct POC line — kept visually and positionally separate from the fib lines so the two are never confused.
• Fibonacci grid (active-leg retracement, plus optional swing-to-swing), with confluence levels marked by a star and a brighter tone.
• Signals: trend-shift triangles on VWAP reclaim/loss; solid reversal labels on band rejections; diamonds and connecting lines for σ-distance divergence; a marker on volatility-squeeze release.
• Status table (single panel): regime, bias, σ-distance, AVWAP, POC, Value Area, squeeze state, divergence, a reversion stop/target/RR template, a data-health row, multi-timeframe regime agreement, and a built-in legend.
• Optional forward projection cone and an optional self-calibration panel that scores how past signals resolved.
Anchor modes
Rolling (fixed bar window), Swing Low, Swing High, or Dual (auto — anchors to the more recent significant pivot). Pivot detection uses bar-count lookbacks (8/13/21/34/55/89), so the entire tool self-scales to any timeframe.
How to use it
1. Read the table first: regime + σ-distance tell you whether price is trending or stretched, and how far from fair value it is.
2. Use the bands as context — near the centerline is fair value; the ±2σ edge is where reversion risk is highest (and the heat fill shades it).
3. Treat reversal labels as fade-the-stretch signals, strongest when the regime is not trending and when a divergence diamond agrees.
4. Use trend-shift triangles (VWAP reclaim/loss) for continuation context.
5. Use fib-confluence stars and the Value Area box / POC as the levels most likely to react.
6. Check multi-timeframe agreement in the table before acting.
7. Optionally turn on the calibration panel to see, on your own symbol and timeframe, how often each signal type has historically followed through.
What makes it original
• A single shared σ framework: bands, regime, divergence, reversals and risk template all read from one volume-weighted standard-deviation measurement around one anchor, rather than bolting unrelated indicators together.
• Reversion-heat channel fill that encodes reversion risk as color density.
• Confluence-filtered reversals — band rejections gated by regime/divergence.
• Volume profile rendered as a separated zone so it never blends into the fib levels.
• A transparent self-calibration panel that scores the script's own signals against a follow-through threshold (descriptive, not a backtest).
Key settings
• Calculation Source — works on any asset/market; default hlc3, switchable to close, hl2, ohlc4, etc.
• Anchor mode and pivot/rolling length.
• Inner/outer band multipliers and fill style.
• Signal sensitivity, session-open filter, reversal-confirmation strictness.
• Table position / text size / legend, and toggles for every module.
Notes and limitations
• Signals are evaluated on closed bars; the σ-distance divergence confirms a few bars after a pivot by design, so it prints late (this is normal for pivot-based divergence and is not repainting of confirmed history).
• Last-bar drawings (profile, fib, projection cone) are redrawn on each new bar and will shift forward — that is expected.
• Asset classes / volume: runs on any market and any timeframe. On instruments that carry real volume (stocks, futures, crypto, etc.) the Anchored VWAP, the volume-weighted σ channel, and the Volume Profile (POC / Value Area) are all fully volume-weighted as intended. On feeds with no real volume (e.g. spot forex, some indices / CFDs) the script still works but degrades gracefully: the VWAP becomes a simple anchored mean, the channel uses an unweighted standard deviation, and the profile becomes a time-at-price distribution. The Data row in the table flags this state as "no-vol / DEGRADED" so you always know which mode you are in.
• The multi-timeframe dashboard uses higher-timeframe requests; you can turn it off to reduce load.
• This is an analysis/visualization tool, not a strategy — it does not place orders and is not optimized or backtested for entries/exits.
Disclaimer
This script is provided for educational and informational purposes only and is not financial, investment, or trading advice. It does not predict future prices. Markets carry risk and you can lose money. Past behaviour of any signal (including the calibration panel) does not guarantee future results. Always do your own research and consider consulting a licensed financial professional before trading. You are solely responsible for your decisions and their outcomes.
Indicator

Confluence Zone Engine [CZE]# Confluence Zone Engine
A structural analysis indicator that identifies support and resistance zones by clustering Anchored VWAPs and Anchored Volume Profile levels across the chart timeframe and up to three higher timeframes. Each zone is rated 1 to 5 stars based on how many independent sources cluster at the level and how diverse those sources are.
This is a structural analysis tool. It marks where multiple independent technical references agree at a price. It does not place trades or suggest entries, exits, targets, stops, or position sizes.
---
## What this script does
The engine runs a six-stage pipeline on every confirmed bar:
**Stage 1 — Pivot detection.** Detects pivot highs and pivot lows at Fibonacci-spaced lengths (3, 5, 8, 13, 21, 34, 55, 89). Each pivot becomes an "anchor" point. Default enabled tiers are 8, 21, and 34 — selected to give fast / medium / slow coverage without redundancy. The full Fibonacci set is configurable.
**Stage 2 — Per-anchor calculations.** For every anchor, the engine maintains:
- An Anchored VWAP (volume-weighted average price since the anchor bar)
- An Anchored Volume Profile, which produces a Point of Control (POC = most-traded price since anchor) and a Value Area (VAH and VAL = upper and lower edges of the 70% volume zone)
So a single pivot generates up to 4 contributor levels: AVWAP, POC, VAH, VAL.
**Stage 3 — Higher-timeframe replication.** The same pipeline (stages 1 and 2) re-runs on up to three configurable higher timeframes via non-repainting `request.security` calls. This produces a multi-timeframe view of structural anchors — pivots and AVWAPs from a 1H chart inform what the 5m engine treats as a higher-timeframe reference.
**Stage 4 — Cluster building.** All contributor levels from all enabled timeframes are collected. The cluster builder walks them in price order, merging any that fall within a configurable tolerance (default 0.08% of current price; preset-adjusted per asset class). A cluster with at least the minimum-count threshold becomes a candidate zone.
**Stage 5 — Star rating.** Each zone is rated 1 to 5 stars based on:
- Total contributor count
- Source-type diversity (how many of the 4 source categories — PH-AVWAPs, PL-AVWAPs, POCs, VAH/VAL — are present)
- HTF agreement (whether contributors from multiple timeframes align)
A "Premium" tier flag fires when top stars combine with HTF agreement.
**Stage 6 — State machine.** Each zone is tracked through a lifecycle:
- **Active** (forming, amber): the zone is currently accumulating contributors
- **Pending** (blue): contributor activity has paused; waiting for price to resolve the level
- **Resolved Support** (green), **Resistance** (red), or **Chop** (gray): determined by whether price moved decisively up, decisively down, or stayed range-bound after the zone activated
- **Tested** (dashed border): price entered the resolved zone but has not closed past the defending edge
- **Broken** (dashed orange + "Broken" label): price has closed past the defending edge
- **Flipped**: if a Broken state confirms over multiple closes past a threshold, the zone repaints to the opposite role (broken Resistance becomes Support, broken Support becomes Resistance)
---
## Why this indicator is original (not a simple mashup)
This is not "AVWAP indicator + Volume Profile indicator + multi-timeframe wrapper." Three design choices distinguish it from existing public indicators:
**1. Anchored at every Fibonacci pivot, not at a single user-selected point.** Standard AVWAP indicators require the user to manually click an anchor point. Standard Volume Profile indicators use either a fixed session or a single anchor. This engine automatically detects pivots at multiple Fibonacci lengths and runs an AVWAP + Volume Profile from each one. The number of active anchors at any time is typically 6 to 20, generating 24 to 80 contributor levels — far more than a manually-anchored tool can produce.
**2. Cross-timeframe clustering, not separate per-timeframe overlays.** The engine does not draw 5 separate AVWAPs from a 1H chart, plus 5 from a 4H, plus 5 from a daily. Instead, levels from all timeframes are collected into one pool and clustered in price space. A 1H AVWAP at 23,720 and a daily POC at 23,718 merge into a single zone marked as "two contributors from two timeframes." This produces structural information neither timeframe shows alone.
**3. Compositional bias from the contributor mix.** The cluster builder records *which type* of contributor formed each zone — pivot-high AVWAPs (trapped sellers' breakevens), pivot-low AVWAPs (trapped buyers' breakevens), POCs (acceptance), VAH or VAL (fair-value edges). The directional implication of each type is summed into a "compositional bias" score. A zone built mostly from PL-AVWAPs and VAL contributions leans support; one built from PH-AVWAPs and VAH contributions leans resistance. This is an analytical lens not present in standard S/R indicators, which generally treat all levels as direction-agnostic.
---
## Mashup justification — how the components work together
The four classes of technical analysis used (pivots, AVWAP, Volume Profile, multi-timeframe analysis) are not chosen arbitrarily. Each contributes a dimension the others do not, and the value comes from how they interact:
**Pivots provide the anchors.** Without pivots, AVWAP needs a manual anchor and Volume Profile needs an arbitrary session. Pivots at multiple Fibonacci lengths give the engine *automatic structural anchors* spanning timescales — short-term swings, intraday swings, session-level swings. The Fibonacci spacing (3, 5, 8, 13, 21, 34, 55, 89) ensures the anchors are non-redundant: each tier has a different bar requirement and catches different swings.
**AVWAP measures participant breakeven from each anchor.** This is the "where might trapped participants defend" dimension. An AVWAP from a pivot high is the volume-weighted breakeven for everyone who entered after that high (mostly net-short positions). An AVWAP from a pivot low is the breakeven for everyone who entered after that low (mostly net-long). When price returns to one of these AVWAPs, structurally those participants are at breakeven and have incentive to act.
**Volume Profile measures acceptance from each anchor.** This is the "what price has been most-accepted by volume" dimension. POC is the most-traded price; VAH/VAL are the edges of the 70%-volume range. AVWAP and POC measure different things — average price vs most-accepted price — and frequently disagree. When they *do* agree at a level, that's two independent signals saying "this price matters."
**Multi-timeframe replication tests for structural agreement.** A zone that exists only on the chart timeframe is one-timeframe noise. A zone where chart-TF contributors *agree with* higher-TF contributors at the same price is structural — the same level shows up no matter which timescale you measure from. The engine treats HTF agreement as a primary input to the star rating: HTF-aligned zones can earn an extra star (capped to prevent inflation).
**The clustering is where the value emerges.** Individually, none of these components produce reliable levels. AVWAP gets broken constantly. POC migrates. Pivot levels get violated. But when the engine sees that the 21-pivot AVWAP, the 34-pivot POC, the 8-pivot VAL, and a 1H AVWAP all land within 0.08% of each other at the same price, that's a confluence of independent references measuring different things — and that *coincidence* is what produces structural significance. The star rating quantifies how much agreement is present.
This is the mashup's purpose: not to combine indicators for their own sake, but to use convergence as a filter that turns individually noisy components into a rated structural signal.
---
## How to use the indicator
**Step 1: Apply to any chart timeframe.** All settings have sensible defaults. The asset-class preset (NSE Index Futures, NSE Stock, US Future, US ETF, US Stock, Commodity, Crypto, or Custom) auto-adjusts cluster tolerance and pivot defaults. Auto-selected higher timeframes scale with the chart — a 5m chart defaults to 15m/60m/240m HTFs, while a daily chart defaults to weekly/monthly HTFs.
**Step 2: Read the status panel (bottom-right).** This is the actionable summary:
- "Sup" row: nearest resolved Support below current price, with point distance
- "Res" row: nearest resolved Resistance above current price, with point distance
- "Top zone": the highest-rated zone overall
- "Data": indicator health (OK / Degraded / Critical) — if the underlying volume data is sparse, ratings are capped
**Step 3: Scan the chart for "Broken" labels.** Any zone in dashed orange with a "Broken" label is currently being violated. Watch for either recovery (border returns solid) or polarity flip confirmation (zone repaints to opposite role).
**Step 4: Find the active amber zone.** This is the current forming confluence. Look at the triangle shape: ▲ means the composition leans support, ▼ means it leans resistance, ◆ means neutral. The number next to the triangle is the star rating. A premium "★" prefix means HTF agreement is present.
**Step 5: Use the Major S/R lines as forward references.** Bold horizontal lines mark the top 2 strongest support levels below current price and top 2 strongest resistance levels above. Labels show price, stars, and distance.
**Step 6: Use the Range band as context.** The translucent aqua band marks the recent trading envelope (default last 50 bars). A narrow band means consolidation; a wide band means trending.
**Step 7: Hover any element for the full breakdown.** Every box, triangle, and line has a tooltip showing total contributors, type counts, HTF alignment, state, and history.
---
## How NOT to use the indicator
- **Do not treat the bias arrow as a trade signal.** It is a compositional description of contributors, not a directional forecast. A zone with a ▲ bias can still resolve as resistance.
- **Do not treat a "Broken" label as a trade trigger.** It tells you a known level is failing — not that you should enter a position in either direction.
- **Do not assume higher stars mean higher profit probability.** Stars measure the diversity and density of contributors, not historical performance or expected return.
- **Do not rely on it for low-volume instruments.** If the data-health badge shows "Degraded" or "Critical," the engine has capped ratings and may suppress zones entirely. This is a feature; the indicator is most accurate on liquid, volume-rich instruments (index futures, large-cap stocks, major crypto).
---
## How to read the star rating
Stars are a descriptive summary of confluence quality. They are not a probability of profit.
- 1 to 2 stars: minimum cluster; one or two source types. Background context.
- 3 stars: at least 5 contributors with 2 or more source types. Recurring intraday levels.
- 4 stars: at least 7 contributors with 3 or more source types, OR 3-star with HTF agreement.
- 5 stars: at least 10 contributors with all 4 source types present. Often boosted by HTF alignment.
By default, only 4-star and 5-star zones get triangle markers and qualify for Top-N or Major S/R lines. This is adjustable.
---
## Visual primitives
- **Confluence zones** — colored boxes marking each cluster. Boxes recolor as zones resolve. Border style indicates compromised state.
- **Triangle markers** — ▲ ▼ ◆ at each formation bar. Shape encodes direction. Color encodes lifecycle state.
- **Top-N S/R lines** — top 4 resolved zones by strength and recency project forward.
- **HTF confluence bands** — semi-transparent bands per higher timeframe (cyan, purple, orange).
- **Major S/R lines** — bold lines for top 2 supports below and top 2 resistances above current price.
- **Range band** — translucent band marking recent trading range with HI / LO labels.
- **Current price line** — thin dotted line at current price.
- **Status panel** — bottom-right summary.
---
## Technical notes
- Pine Script v6
- Non-repainting: all `request.security` calls use `barmerge.lookahead_off`
- Asset-class presets adjust cluster tolerance and pivot defaults
- Built-in data-integrity layer caps ratings when volume data is sparse or stale
- Seven alert conditions: new zone formed, high-quality (4 to 5 star) zone, HTF aligned, price entered support, price entered resistance, data health degraded, polarity flip
---
## Important risk disclosure
This indicator is provided for educational and informational purposes only and is not financial advice. Trading and investing involve substantial risk of loss, including the possible loss of all invested capital. The zones, ratings, bias shapes, and lines are descriptive summaries of structural confluence — they are not predictions of future price movement, indications of profitability, win rate, or expected return.
No backtested or hypothetical performance is claimed or implied. Past zones identified by the indicator are not indicative of future results.
You are solely responsible for any decisions you make. Consult a qualified, licensed financial advisor before trading. Past performance does not guarantee future results.
Indicator

Anchored VWAP Risk Ladder [AGPro Series]Anchored VWAP Risk Ladder
🧠 Core Idea
After an important market event, is price trading close to fair value or becoming extended relative to the anchored VWAP?
📌 Overview / What it does
Anchored VWAP Risk Ladder builds a volume-weighted average price from a selected anchor event and turns the distance from that anchor into a structured risk ladder.
The script displays anchored VWAP, volume-weighted deviation bands, right-side ladder tags, reclaim and lose labels, extension context, and a compact AG Pro panel with distance, score, risk ladder, and action state.
It does not predict price direction, automate trades, or claim that anchored VWAP will hold as support or resistance. It organizes event-based volume-weighted context into a readable chart framework.
🎯 Purpose & Design Philosophy
Anchored VWAP is often useful after a meaningful event, but raw AVWAP alone can be difficult to interpret without context.
This script was built to answer a practical question: how far is price from the anchored value area, and is that distance becoming useful, balanced, or risky?
The design supports traders who think in terms of anchored fair value, risk distance, reclaim behavior, and extension zones.
⚡ Why This Script Is Different
Most VWAP tools show a line and leave interpretation fully manual.
This script does NOT stop at plotting anchored VWAP.
Instead, it builds a complete risk ladder around the anchor, adds deviation context, scores reclaim or lose behavior, and summarizes the current state in a clean dashboard.
⚙️ Methodology
1. Anchor Detection
The script can anchor from manual time, high-volume events, swing pivots, session open, week open, or month open.
2. AVWAP Calculation
From the active anchor, the script accumulates volume-weighted price and volume-weighted variance to calculate anchored VWAP and deviation bands.
3. Risk Ladder Mapping
Distance from anchored VWAP is measured in ATR and deviation terms to classify whether price is near value, inside Band 1, inside Band 2, or extended.
4. Visual Output
The script plots AVWAP, upper/lower deviation bands, ladder fills, event labels, right-side tags, bar state color, and a dashboard.
🗺️ How to Read the Chart
The AVWAP rail represents the volume-weighted average price from the active anchor.
Deviation bands represent the ladder around anchored value.
Labels mark anchor events, AVWAP reclaim events, AVWAP lose events, and optional extension-risk conditions.
The panel shows:
• Anchor → current anchor type and age
• Distance → price distance from AVWAP in ATR
• Risk Ladder → current ladder zone and risk score
• Score → current context score and direction state
• Action → READY / MONITOR / WAIT / BLOCKED
🚦 Signals & States
• Anchor Locked → a new event anchor has been selected
• Ready Reclaim → price has reclaimed anchored VWAP with enough context score
• Ready Lose → price has lost anchored VWAP with enough context score
• Near AVWAP → price is close to anchored value
• Band 1 / Band 2 → price is moving away from anchored value
• Extended → distance from AVWAP is elevated
🔔 Alerts Logic
Alerts can trigger when a new anchor is locked, when price reclaims AVWAP, when price loses AVWAP, or when extension-risk conditions appear.
Alerts are attention markers only. They do not represent trade instructions or guaranteed outcomes.
🧩 Confluence Logic
The context becomes stronger when anchored VWAP reclaim or lose behavior aligns with relative volume, acceptable distance, and a clear ladder state.
The risk ladder helps separate balanced conditions from extension conditions.
📊 When to Use
• After high-volume market events
• Around earnings, news, breakout, or liquidation-style candles
• During trend continuation pullbacks
• When studying institutional average price context
• On liquid symbols with meaningful volume data
⚠️ When NOT to Use
• Very low-liquidity symbols
• Markets with unreliable or synthetic volume
• Extremely choppy conditions where anchors reset too often
• Situations where the selected anchor is not meaningful
• When using AVWAP as a standalone trading signal
🎛️ Key Inputs
• Anchor Mode → controls how AVWAP is anchored
• Manual Anchor Time → user-defined anchor timestamp
• High Volume Anchor Threshold → controls automatic high-volume anchors
• Deviation Band 1 / 2 → controls ladder width
• Extension Risk ATR → controls when distance becomes elevated
• Minimum Ready Score → controls reclaim or lose strictness
• Visual Settings → control bands, labels, tags, panel, and bar colors
🖥️ Interface & Visual Design
The interface is built for fast visual hierarchy.
AVWAP is the central reference, deviation bands define the risk ladder, right-side tags make the ladder readable, and the panel summarizes state without forcing the user to inspect every line manually.
🧪 Practical Usage Workflow
1. Choose the anchor mode
2. Read the active anchor and distance in the panel
3. Check whether price is near AVWAP or extended
4. Watch reclaim or lose labels around AVWAP
5. Use broader structure and risk context before making any decision
🔍 Interpretation Guidelines
Price near AVWAP often represents a balanced value area relative to the anchor.
Price far from AVWAP may represent stronger trend behavior, but it may also carry extension risk.
READY states mark meaningful reclaim or lose behavior, not certainty.
🚫 What This Script Is NOT
This script is not a prediction engine.
It is not an automated trading system.
It does not guarantee support, resistance, continuation, reversal, or profit.
It is not financial advice.
⚠️ Limitations & Transparency
Anchored VWAP quality depends heavily on anchor selection.
Different timeframes may produce different anchor timing and visual structure.
Volume data quality may vary between symbols, brokers, and exchanges.
Deviation bands are statistical references, not fixed market boundaries.
🧠 Market Context Notes
Anchored VWAP works best when the anchor represents a meaningful market event.
High-volume displacement, swing pivots, session opens, weekly opens, and monthly opens may each tell a different story.
The user should choose the anchor mode that best fits the market question.
🧾 Use Case Examples
When a high-volume candle creates a new anchor, the script tracks whether price remains near the anchored value area or begins to extend away from it.
When price reclaims AVWAP with enough score, the script marks a READY reclaim context.
When price loses AVWAP with enough score, the script marks a READY lose context.
🧱 System Philosophy
AGPro Series tools are built as decision-support engines.
The purpose is to structure market context into readable zones, states, scores, and risk references without turning analysis into blind signal-following.
🔐 Non-Promise Statement
No script can provide certainty.
No AVWAP level guarantees a reaction.
No signal guarantees continuation, reversal, or profit.
📉 Risk Disclosure
Trading involves risk.
Users are responsible for their own analysis, decisions, risk management, and execution.
This script is for educational and analytical purposes only and does not provide financial advice.
📚 Educational Note
Use this tool to study how anchored value, volume-weighted distance, deviation bands, reclaim behavior, and extension risk interact across different market conditions.
Indicator

Pymander's EZ VWAPPymander's EZ VWAP
Standard VWAP indicators are great, but let’s be honest—they can be a bit "static." They show you where the price is relative to an average, but they don't tell you the story of the price action. That’s why I built EZ VWAP.
This isn't just a line on your chart; it’s a complete decision-making system designed to help you distinguish between a healthy trend and a trap.
What makes EZ VWAP stand out?
Most VWAPs just give you ±1, ±2, and ±3 standard deviations and call it a day. EZ VWAP is smarter. It classifies the market into logical zones:
The Fair Value Zone (±0.5σ): This is the "Chop Zone." If price is hanging out here, there’s no clear edge. We stay patient.
The Extension Zone (±1σ to ±2σ): This is where the magic happens for mean reversion.
The Exhaustion Zone (Beyond ±3σ): The "Danger Zone" where trends either blow off or reverse violently.
🛠️ Key Features You Won't Find in a Basic VWAP:
Acceptance vs. Rejection Logic: The biggest VWAP trap is shorting a "stretch" only for the price to keep mooning. Our Sweep + Reclaim signals only trigger when the price fails to hold above a band. It asks: "Did price accept the new high, or did it reject it?"
Momentum Dashboard: A quick-glance table in the corner tells you if the VWAP slope is Accelerating (momentum is expanding) or Decelerating (trend is weakening).
Dynamic Slope Coloring: The VWAP line itself changes color based on its "speed." Bright colors for strong trends, and neutral colors for weakening moves—perfect for timing your entries.
Three Modes in One: Whether you want a standard Session reset, a specific Anchored point (like a news event), or a Rolling window for a more responsive feel, we’ve got you covered.
Tailored Entries: Choose between Aggressive, Balanced, or Conservative entry models to match your personal risk tolerance.
How it helps you:
EZ VWAP stops you from "catching falling knives" by waiting for price to actually reclaim a level before signaling an entry. It helps you stay out of the chop and focus on the high-probability "stretch" areas where the big moves happen.
I’d love to hear how it’s working for you! If you have ideas for new features or tweaks, drop some feedback in the comments.
Wishing you all tons of luck and many, many green days!
-Pymander Indicator

Percentile Stretch Bands [AGPro Series]Percentile Stretch Bands
🔹 OVERVIEW
Percentile Stretch Bands is an empirical, distribution-free overextension map. Instead of plotting standard deviation envelopes that assume a normal distribution of price behavior, this indicator samples the actual historical distance between price and a chosen reference (EMA, VWAP, or Anchored VWAP) and draws context-specific Stretch and Extreme bands directly from the empirical percentile distribution. The result is a visual reference of how stretched price is relative to its own historical behavior, adapted to the asset and timeframe being viewed.
🔹 UNIQUE EDGE
Most "stretch" or "volatility band" tools on the platform rely on parametric assumptions — standard deviation multipliers, ATR multiples, or fixed percentage offsets. These approaches collapse when the underlying return distribution is skewed, fat-tailed, or regime-dependent, which is the rule rather than the exception across crypto and FX assets.
Percentile Stretch Bands takes a different path:
• Distribution-free: bands are drawn from the actual empirical percentile of price-to-reference distance, not from a Gaussian assumption.
• Side-specific sampling: upper and lower distances are collected into separate samples, so asymmetric behavior (trending markets, one-sided regimes) is preserved rather than averaged away.
• Regime-aware rendering: when Focus Active Side is enabled, each bar displays only the side relevant to price position, producing a clean single-story chart without visual competition.
• Readiness gating: bands appear only once a minimum number of observations is reached on the active side, with the status panel clearly indicating the collection stage.
🔹 METHODOLOGY
For every bar in the configured lookback window, the signed percent distance between close and the selected reference is computed and partitioned into two historical samples: positive distances (upper extensions) and negative distances in absolute terms (lower extensions).
Each sample is sorted and two percentile cut-offs are extracted independently:
• Stretch percentile (default 80) — the threshold beyond which a distance is considered materially extended.
• Extreme percentile (default 95) — the threshold beyond which a distance is statistically rare within the chosen lookback.
These cut-offs are then translated from percent-distance back into absolute price bands around the active reference, producing four levels: Upper Stretch, Upper Extreme, Lower Stretch, Lower Extreme. The current distance is also ranked against its side's sample and displayed as an ordinal percentile (for example, "Upper P87") in the status panel.
🔹 SIGNALS AND ALERTS
The indicator is a visual overextension map and does not generate directional trade signals. Four alert conditions are exposed for users who want to be notified of boundary events:
• Upper Stretch Cross — close crosses above the Upper Stretch band.
• Upper Extreme Cross — close crosses above the Upper Extreme band.
• Lower Stretch Cross — close crosses below the Lower Stretch band.
• Lower Extreme Cross — close crosses below the Lower Extreme band.
These alerts mark entries into statistically extended zones relative to the empirical sample. They are contextual flags, not trade recommendations.
🔹 KEY INPUTS
Reference
• Reference Mode — EMA, VWAP, or Anchored VWAP baseline
• EMA Length — smoothing length for the EMA reference
• AVWAP Anchor Time — starting timestamp for Anchored VWAP
Statistics
• Lookback — bars used to build the empirical distribution (default 500)
• Minimum Side Sample — observations required before bands appear
• Stretch Percentile — primary extension threshold (default 80)
• Extreme Percentile — rare-extension threshold (default 95)
Display
• Focus Active Side — regime-aware single-story rendering
• Show Active Stretch Zone Box — right-side zone anchor on the active side
• Zone Forward Projection — forward visibility of the active zone
• Band Color Profile — Soft, Premium, or Bold
• Panel Text Size and Label Text Size — Small, Normal, or Large
Level Tags
• Show Level Tags, Show Reference Tag, Tag Mode, Tag Offset Bars
🔹 HOW TO USE
1. Select a reference that fits the asset and timeframe. EMA is a robust default across all instruments. VWAP is suited to intraday equities and futures. Anchored VWAP is used when a specific event origin (earnings, news, structural low) is relevant.
2. Let the status panel reach the "Ready" state. The panel reports active samples and readiness — bands are intentionally withheld until the side-specific sample is sufficient.
3. Read the current percentile rank in the Zone cell. Values near the center indicate price trading close to the reference; values approaching P95 or above indicate the sample's rare extensions.
4. Treat Stretch and Extreme bands as context, not as triggers. A move into the Extreme zone reflects a statistically rare extension on the chosen sample, not a directional signal.
5. Combine with structural tools — trend context, market structure, higher-timeframe bias — before any discretionary decision.
🔹 LIMITATIONS AND TRANSPARENCY
• The indicator is descriptive, not predictive. Percentile bands describe past behavior within the lookback window; they do not forecast future price action.
• Regime shifts can temporarily invalidate historical bands. A sudden volatility expansion will push price beyond extreme levels while the sample re-stabilizes.
• Empirical percentiles require sufficient observations. On very new symbols or short lookbacks, the "Collecting" state is the correct and expected behavior.
• Anchored VWAP mode depends on a meaningful anchor choice. A poorly chosen anchor produces a reference line without structural relevance.
• The active stretch zone box is a visual anchor for screenshots and review, not a projection of future levels.
🔹 RISK DISCLOSURE
This script is a visual analytics tool and is not a strategy, signal service, or financial advice. It does not place orders, manage positions, or recommend directional exposure. Trading involves risk of loss. Users are responsible for their own analysis, risk management, and trading decisions. Indicator

Multi-Anchor VWAP Grid [AGPro Series]Multi-Anchor VWAP Grid
🔹 Overview
Multi-Anchor VWAP Grid is a volume-weighted analysis tool that plots five independently anchored VWAP lines on the same chart — anchored from swing high, swing low, higher-timeframe pivot, all-time high, and session open. Each anchored VWAP includes optional ±1σ and ±2σ standard deviation bands, forming a dynamic grid of volume-weighted support and resistance levels. When three or more VWAPs converge within a tight ATR-based band, the indicator draws a rectangular confluence zone highlighting the area as a higher-probability price reaction region.
The script is fully automatic. All five anchors are detected by internal engines (pivot detection, session detection, timeframe change detection, all-time-high tracker) and require no manual date picking or retroactive anchor placement. Install the indicator, select which anchors you want active, and the grid builds itself.
🔹 What It Does Differently
Most anchored VWAP tools plot one anchor at a time and require the user to manually place the anchor each time a new swing or event is identified. This script plots five anchors simultaneously and lets them compete for relevance. When multiple independent anchors agree on a price level, that agreement itself becomes the signal — visualized as a confluence zone. A single VWAP is one data point. Five VWAPs intersecting within 0.5 ATR of each other is a structural event.
The confluence detection engine tests each active VWAP as a reference point, counts how many others fall within the user-defined ATR tolerance, and picks the densest cluster on each bar. A minimum VWAP count threshold (default 3) prevents noise, and a lifecycle manager extends, adaptively resizes, and expires zones based on bar age and midpoint drift.
🔹 Methodology
**Anchor engines**
Swing High and Swing Low VWAPs reset on each confirmed pivot using the standard ta.pivothigh / ta.pivotlow detector with a configurable lookback length. HTF Pivot VWAP resets at the start of each selected higher-timeframe period (daily, weekly, or monthly) using timeframe.change. ATH VWAP resets whenever a new all-time high is printed on the visible chart. Session Open VWAP resets at the first bar of each trading session defined by the session window input.
**VWAP calculation**
Each anchor maintains three running accumulators since its last reset: sum of (price × volume), sum of volume, and sum of (price² × volume). VWAP is computed as the first divided by the second. Standard deviation is derived from the variance identity: sqrt(E − E ²), where E and E are computed from the running accumulators. Bands are plotted at configurable multipliers of this running standard deviation.
**Confluence engine**
On each bar, the script evaluates every active VWAP as a potential cluster center. For each candidate center, it counts how many other active VWAPs fall within ATR × tolerance distance. The cluster with the highest count wins. If the winning count meets or exceeds the minimum threshold, the bar is marked as confluence-active.
**Zone lifecycle**
When confluence becomes active, a new rectangular zone is created spanning the min/max of the clustered VWAPs. As long as confluence remains active and the cluster midpoint drifts less than 0.5 ATR from its original midpoint, the zone extends to the current bar and adaptively resizes with rate-limited expansion (maximum 1 ATR growth per bar per direction, preventing erratic stretching). If the midpoint drifts more than 0.5 ATR, a new zone is created. A 5-bar debounce prevents micro-breaks in confluence from prematurely closing active zones. Zones auto-expire after a configurable age limit (default 120 bars).
🔹 Signals and Panel Readouts
The information panel in the top-right corner (position and theme configurable) displays:
- **Price Bias** — count of VWAPs price is currently above vs below, with an overall BULL / BEAR / MIXED classification
- **Confluence** — current status (active with cluster count, or none) and the minimum-count threshold in use
- **Closest VWAP** — which of the five VWAPs is currently closest to price, and the distance in ATR units
- **Active VWAPs** — each enabled VWAP's current value and percent distance from close
Two alert conditions are built in: new confluence zone detection, and price crossing any active VWAP line.
🔹 Key Inputs
**Anchor Points group** — toggle each of the five VWAPs on or off, set swing pivot lookback length, choose HTF timeframe (D/W/M), define the session window for intraday anchoring.
**Deviation Bands group** — toggle bands on or off, configure band 1 and band 2 multipliers, enable or disable gradient fills between VWAP and the first band.
**Confluence Zones group** — toggle zones on or off, set minimum VWAPs required for a confluence (2 to 5), adjust the ATR-based tolerance, define maximum zone age in bars.
**Panel group** — toggle panel, choose location (six positions), select Dark or Light theme, set font size (Small / Normal / Large).
**Labels group** — toggle the compact end-of-line labels that identify each VWAP at the right edge of the chart.
🔹 How to Use
This indicator is designed as a context layer, not a standalone entry signal. Suggested workflow:
**1. Identify structural bias.** Check the Price Bias row in the panel. If 4 or 5 VWAPs sit below price (BULL), the market is trading above its most relevant volume-weighted averages across multiple timeframes and event contexts. The opposite applies for BEAR.
**2. Watch for confluence formation.** When the panel shows Confluence ACTIVE with 3 or more VWAPs clustered, a meaningful volume-weighted support or resistance area is forming. These zones often precede reaction or reversal behavior.
**3. Use bands for context.** When price trades near the ±1σ band of a single VWAP, reversion back toward that VWAP is statistically more likely. ±2σ extensions indicate volatility outliers.
**4. Cross-reference with your own tools.** This script is most useful combined with price action, volume profile, or a trend filter of your choice. It does not generate entries or exits on its own.
🔹 Tips
- On crypto 24h markets, set Session Window to 0000-2359 for a full-day session VWAP.
- Higher Swing Pivot Length values (30–50) filter noise on higher timeframes; lower values (10–15) are better for intraday.
- If the chart feels visually crowded, disable the ±2σ bands or reduce the number of active anchors. All five are rarely needed simultaneously.
- For the strongest confluence signals, increase Min VWAPs for Confluence to 4 — rarer but higher conviction.
🔹 Limitations and Transparency
- The script uses standard Pine Script pivot detection for swing anchors. Pivots are confirmed only after the pivot length has passed, which means swing VWAP anchors are placed retrospectively by that many bars. This is an inherent limitation of all pivot-based tools, not a bug.
- ATH tracking is limited to the visible chart range. On timeframes or symbols where the chart does not load full history, the "ATH" anchor represents the highest point within loaded data, not the true all-time high.
- Standard deviation bands assume price dispersion around each VWAP is approximately normal over the anchored period. In strongly trending markets, this assumption weakens and bands may widen significantly.
- Confluence zones are descriptive, not predictive. They mark areas where multiple volume-weighted averages happen to agree. They do not guarantee price reaction, only indicate where reaction is more plausible than average.
- Session Window input must match the instrument's trading hours to produce a meaningful intraday VWAP. Incorrect session definitions will produce misleading anchor points.
🔹 Risk Disclosure
This indicator is provided for educational and analytical purposes only. It is not financial advice, investment advice, or a recommendation to buy, sell, or hold any asset. All trading involves substantial risk of loss. Past chart behavior and historical VWAP reactions do not guarantee future results. Users are solely responsible for their own trading decisions and risk management. Always combine indicator output with independent analysis and appropriate position sizing. The author accepts no responsibility for any financial outcome resulting from the use of this script. Indicator

AG Pro Anchored VWAP Event Map [AGPro Series]AG Pro Anchored VWAP Event Map
Overview / What it does
AG Pro Anchored VWAP Event Map is an overlay built to organize price action around Anchored VWAP after a meaningful starting point has been defined. Instead of treating VWAP as a single static reference, this script focuses on the relationship between price and a chosen anchor, then maps how the market behaves after that anchor is established. The goal is not to forecast price, but to make post-anchor structure easier to read in a consistent visual framework.
The script supports three anchor paths: Open, Swing, and Event. Open mode can reset the anchor from a daily, weekly, or monthly opening context. Swing mode rebuilds the anchor from a confirmed pivot high or pivot low. Event mode is designed for expansion-type situations and can anchor from a range expansion, a volume spike, or a breakout impulse. This creates a flexible workflow for traders who want to study how price responds to AVWAP under different structural conditions without switching tools.
Once the anchor is set, the script plots the Anchored VWAP, builds a distance band around it, tracks reclaim and reject behavior, and summarizes the current post-anchor bias in a compact panel. The result is a clean event map that can be used to study acceptance, rejection, recovery, or continuation around an anchored reference level. It is meant to simplify interpretation, not replace market context.
A key design goal of this script is clarity. The visual package is intentionally structured so the anchor, AVWAP path, distance zone, signal labels, and bias panel can be read together without turning the chart into a dense signal board. In practice, that means the indicator is most useful when it is treated as a contextual decision-support tool rather than a standalone trigger engine.
Unique Edge
The main distinction of this script is that it is not built as a generic VWAP overlay. Its emphasis is on post-anchor behavior. That means the visual logic starts from the selected anchor event and then evaluates how price interacts with the anchored VWAP afterward. In other words, the anchor is not only a starting point for the line itself; it is the center of the script's interpretation model.
Another differentiator is the combination of multiple anchor sources within one workflow. Traders can use opening-session logic, confirmed swing logic, or event-driven logic depending on the type of market behavior they are studying. This makes the indicator suitable for different styles of chart review while keeping the interface straightforward.
The distance band adds a second layer of structure. Rather than reading only the AVWAP line, users can also see whether price is operating close to the reference, stretched around it, or reacting from the upper or lower band zone. This helps frame whether a move appears to be re-accepting the anchored average, rejecting away from it, or trading in a more extended state.
The script also tries to keep the signal layer readable through selective label logic. Reclaim and reject markers are not intended to flood the chart. They are there to mark notable interactions with the anchored framework, while the panel provides a compact summary of the active anchor, current bias, distance, and latest signal state.
Methodology
The script begins by defining an anchor source. In Open mode, the anchor can be tied to a daily, weekly, or monthly opening transition. In Swing mode, the script waits for a confirmed pivot high or pivot low based on the selected swing length. In Event mode, the anchor is created only when a qualifying market event appears according to the selected event model.
For event-based anchoring, the script can use one of three internal conditions. Range Expansion looks for directional range behavior relative to ATR and recent structure. Volume Spike looks for directional participation with higher-than-average volume and a meaningful candle body fraction. Breakout Impulse looks for directional movement through recent extremes with supportive range and volume characteristics. These are practical anchor candidates for traders who want the AVWAP to begin from a meaningful change in behavior rather than from a calendar reset.
After the anchor is created, the script calculates Anchored VWAP using cumulative price-volume data relative to that anchor point. From there, it builds a distance band around the AVWAP. The band can be defined by ATR or percentage mode, depending on whether the user prefers a volatility-based or proportional framework.
Post-anchor bias is then derived from a simple internal score. The script evaluates whether price is above or below AVWAP, whether the AVWAP slope is improving or weakening, and whether price is trading beyond the distance band. This produces a practical Bullish, Bearish, or Neutral state. The intention is not to compress market structure into a perfect score, but to provide a compact directional read that can be used alongside the chart.
Reclaim and reject logic is based on how price interacts with the AVWAP and the surrounding band after the anchor is active. A reclaim highlights price moving back through the anchored reference with confirmation, while a reject highlights failure or pushback behavior around the band area. These events are intended as structural observations rather than guaranteed trade setups.
Signals & Alerts
The script includes reclaim and reject signal logic for both directions. These labels are designed to call attention to notable interactions with the anchored framework after the selected anchor becomes active. In practical use, reclaim behavior can be interpreted as a sign that price is attempting to re-establish acceptance relative to AVWAP, while reject behavior can suggest rejection away from the mapped zone.
Because market structure can become noisy, the script also includes signal spacing and density controls to reduce repetitive label clutter. This is especially relevant when anchored conditions remain active for long periods and price repeatedly tests the same area. The goal is to preserve readability while still marking relevant interactions.
Alert conditions are included for bullish reclaim, bearish reclaim, bullish reject, bearish reject, and a broader any-signal state. These alerts are deterministic within the script's ruleset, but they should still be used as workflow tools rather than interpreted as self-sufficient trading instructions.
Key Inputs
Anchor Source:
Choose whether the indicator should anchor from Open, Swing, or Event logic.
Open Anchor Type:
In Open mode, select daily, weekly, or monthly opening context.
Swing Length:
Controls how confirmed pivot highs and lows are detected in Swing mode.
Event Type:
In Event mode, choose between Range Expansion, Volume Spike, or Breakout Impulse as the anchor trigger model.
Event Lookback / Multipliers / Cooldown:
These inputs control how strict the event selection becomes and how frequently new event anchors can appear.
Band Mode:
Switch between ATR-based and percentage-based distance bands.
ATR Band Multiplier / Percent Band:
Define the width of the distance zone around Anchored VWAP.
Signal Density:
Helps regulate how aggressively reclaim and reject labels are displayed.
Panel and Label Size:
Allows the visual layout to remain readable across different chart styles and screen sizes.
Show Anchor Label / Show Anchor Level / Show Bias Ribbon:
These toggles control the visibility of anchor-focused visual elements and optional bias coloring.
Limitations & Transparency
This script is an interpretation aid. It does not identify the single correct anchor for all market environments. Different anchor choices can lead to different AVWAP paths, different reclaim or reject readings, and different conclusions. That is normal, and it is one of the reasons the script provides multiple anchor modes.
Event-based anchors depend on internal threshold logic such as ATR expansion, volume conditions, and breakout behavior. On some symbols or timeframes, those filters may trigger more frequently or less frequently than expected. Users may need to adjust event sensitivity and band settings to fit the market they are analyzing.
Reclaim and reject states are rule-based. They are not a guarantee of continuation, reversal, or follow-through. In sideways conditions, repeated AVWAP interactions can occur without producing a sustained directional move. The script can help organize those interactions visually, but it cannot remove market uncertainty.
The post-anchor bias is intentionally simplified. It is designed for readability, not for complete market classification. It should be read together with broader price structure, higher-timeframe context, liquidity conditions, and user-defined execution rules.
Risk Disclosure
This indicator is for chart analysis and workflow support. It does not provide financial advice, investment advice, or guaranteed outcomes. Markets involve risk, and any trading or investing decision remains the sole responsibility of the user.
No indicator can remove uncertainty from live markets. Anchored VWAP, reclaim behavior, reject behavior, and bias states are analytical references only. They should be validated with independent judgment, risk management, and broader market context before being used in any decision-making process.
Use this script as a structured visualization tool, not as a promise of performance or a substitute for disciplined trade planning.
Indicator

Indicator

TetraTrend Engine [MarkitTick]💡 The TetraTrend Engine is an advanced, multifaceted overlay indicator designed to provide traders with a comprehensive view of market structure, trend direction, and institutional liquidity levels. By capturing and freezing critical moving average data at a user-defined moment in time, it transforms lagging indicators into static support and resistance frameworks. Furthermore, it integrates a sophisticated Multi-Timeframe (MTF) confluence matrix, ADX-based chop filtering, and dynamic position sizing, making it a complete suite for methodical trade execution. Please note that if applied to non-standard charts (like Heikin Ashi or Renko), the script's calculations may repaint.
✨ Originality and Utility
Standard moving averages constantly adjust to new price data, which is useful for trailing trends but less effective for identifying historical break-and-retest zones. This script introduces a novel "Freeze Point" mechanic. At a specific, fixed date and time, the engine captures the exact values of four distinct moving averages and the Average True Range (ATR). These values are then projected forward as horizontal levels, creating a persistent architectural map of the market based on a fundamental historical event (like an earnings report, macroeconomic news release, or structural pivot). Combined with an Auto-Anchored VWAP that automatically initiates from this exact freeze date, it offers a highly unique, institutional-grade perspective on volumetric average price versus static historical momentum.
🔬 Methodology and Concepts
● Core Trend Identification
The indicator calculates four separate moving averages, with default lengths of 20, 50, 100, and 200.
Users can toggle the calculation method between Simple (SMA), Exponential (EMA), Weighted (WMA), and Volume-Weighted (VWMA) moving averages.
● The Freeze Engine
A timestamp is set by the user (defaulting to a specific date like "2025-12-31 23:59").
Once the market time crosses this threshold, the script triggers a state where calculations are locked.
It records the exact values of the four MAs and the 14-period ATR at that exact candle.
● Institutional Confluence and Risk Matrix
The script checks higher timeframe (HTF) trend alignment using a primary HTF filter (defaulting to Daily).
An optional MTF Matrix requires alignment across three custom timeframes (e.g., 240m, Daily, Weekly) before validating any bullish signals.
It incorporates an ADX threshold (default 20.0) to filter out choppy, ranging markets, ensuring signals are only generated during periods of active momentum.
🎨 Visual Guide
● Chart Overlays and Lines
MA 1 (Length 20): Plotted in bright Cyan (#00E5FF).
MA 2 (Length 50): Plotted in Teal (#14B5CB).
MA 3 (Length 100): Plotted in Royal Blue (#2979FF).
MA 4 (Length 200): Plotted in Purple (#AA00FF).
Freeze Marker: A vertical line (default Dashed, colored Gray/Blue) denotes the exact moment the historical levels were captured.
Anchored VWAP: If enabled, an Orange line (#FFB74D) plots the volume-weighted average price starting precisely from the Freeze Marker.
● Dynamic Liquidity Zones
If enabled, semi-transparent shaded bands appear around Frozen Level 1 and Frozen Level 4.
These bands represent a distance of 0.5 * Frozen ATR, illustrating expected volatility boundaries at the time of the freeze.
● Analytics Dashboard
A heads-up display table is drawn in the top-right corner, displaying a dark theme with blue/gray borders.
It lists the HTF Trend Status (Bullish in Green, Bearish in Red).
It displays the current Market State (Trending/Active vs. Chop/Low Vol) based on the ADX.
It shows current Volatility (ATR) and ADX Strength.
If enabled, it outlines the MTF Matrix Status and the mathematically calculated Dynamic Position Size.
● Signal Shapes and Labels
A green triangle pointing up (#00E676) plots below the bar when a valid Long signal is generated.
Dynamic labels attach to the right side of the frozen levels, constantly updating to show the MA length and exact price level.
📖 How to Use
● Setting the Anchor
Identify a major market event on your chart (a swing high/low, a CPI data release, or a sudden volume spike).
Open the settings and input the exact date and time of this event into the "Fixed Date/Time (Freeze Point)" input.
● Interpreting Signals
Wait for the market to interact with the freshly drawn horizontal frozen levels.
A valid Long signal (Green Triangle) will only trigger if: the price crosses above Frozen Level 1, the HTF trend is bullish, the market is not ranging (ADX > threshold), and the optional MTF matrix is fully aligned.
Monitor the Analytics Dashboard table to ensure the broader market environment supports the trade setup.
⚙️ Inputs and Settings
• Moving Average Settings
Length 1 through 4: Adjust the lookback periods for the core trend calculation.
MA Type: Dropdown to select the mathematical smoothing method (SMA, EMA, WMA, VWMA).
• Advanced Filters & Risk
Primary HTF Filter: Determines the baseline higher timeframe to establish the primary trend direction.
ADX Chop Filter Threshold: Sets the minimum ADX value required to consider the market "trending" rather than "ranging".
Risk/Reward Ratio: A multiplier used to automatically calculate Take Profit 1, 2, and 3 targets based on the dynamically calculated Stop Loss distance.
• Institutional Features (Optional)
Enable Auto-Anchored VWAP: Anchors a VWAP strictly starting from the chosen Freeze Date.
Enable MTF Confluence Matrix: Requires alignment across three separate, user-defined timeframes.
Enable Dynamic Position Sizing: Inputs for Account Size ($) and Risk Per Trade (%). The script uses the ATR-based stop loss to output exact contract/share sizing required to maintain strict risk parameters.
🔍 Deconstruction of the Underlying Scientific and Academic Framework
The TetraTrend Engine leverages several established quantitative and statistical concepts to derive its signals. Moving averages serve as low-pass filters, dampening high-frequency market noise to reveal the underlying directional component of the time series. By capturing these values statically at a user-defined vector (the Freeze Point), the script transitions from dynamic time-series analysis to fixed architectural support/resistance theory, positing that historical mean values at critical temporal nodes retain psychological and institutional relevance.
Furthermore, the integration of the Average Directional Index (ADX) relies on the statistical measurement of trend velocity and momentum dispersion. The ADX component acts as a volatility gatekeeper, mathematically ensuring that the standard deviation of directional movement exceeds a baseline threshold before capital is deployed. Position sizing calculations utilize the Average True Range (ATR)—a measure of absolute price dispersion—to dynamically scale risk exposure inversely to market volatility, ensuring normalized risk parity across varied market environments.
⚠️ Disclaimer
All provided scripts and indicators are strictly for educational exploration and must not be interpreted as financial advice or a recommendation to execute trades. I expressly disclaim all liability for any financial losses or damages that may result, directly or indirectly, from the reliance on or application of these tools. Market participation carries inherent risk where past performance never guarantees future returns, leaving all investment decisions and due diligence solely at your own discretion. Indicator

Linear Regression [Anchored, Band, Signals]OVERVIEW
This indicator is a statistical analysis tool that plots linear regression channels alongside dynamic deviation bands. It aims to provide a flexible framework for observing price distribution and momentum quality without making predictive claims.
ORIGINALITY
This indicator provides advanced options for linear regression-based analysis.
📌 Allows setting the calculation window length based on a fixed bar count or an anchored timeframe.
📌 Draws regression channels in either linear or logarithmic scales.
📌 Identifies historical highest and lowest limits in addition to standard deviation levels.
📌 Displays the non-repainting history of the channel via the "Historical Plots" option.
📌 Calculates Pearson's R (correlation strength) and the Theta (θ) angle (the slope of the channel).
📌 Generates Long and Short signals using two distinct filters and four different channel strategies.
📌 Generates alerts based on signals.
📌 Includes dynamic visualization options. Also displays the precise values of the calculated metrics in the Data Window.
WHAT IS LINEAR REGRESSION?
Linear regression is an analytical method used to calculate a dependent variable based on independent variables when a cause-and-effect relationship exists between them. In this context, the dependent variable is the price, and the independent variable is the time or bar_index. It aims to model the potential behavior of price action based on this relationship. A regression channel is calculated based on the sample deviation and its multiples. Consequently, it is widely utilized to determine dynamic support and resistance levels.
REPAINTING AND THE SOLUTION
Repainting can be briefly defined as the alteration of past data values in subsequent bars. Because a standard regression channel is recalculated by shifting the array with every new bar, drawings based purely on line functions inherently repaint. However, this indicator overcomes the repainting issue through its "Historical Plots" feature. This option allows users to dynamically observe the true historical states of the channel levels. The signal mechanics of the indicator are also built strictly upon this non-repainting framework to ensure execution integrity.
APPLICATIONS
The data provided by this tool can be applied in various observational contexts. When prices stretch significantly toward the outer deviation bands, it highlights mathematical extremes that traders often view as potential mean-reversion zones. Conversely, when the price breaks outside the primary boundaries with a high Theta angle, it signals a statistically significant momentum shift. By utilizing the built-in Pearson's R correlation, observers can quantitatively filter out sideways, low-momentum periods (choppy markets) and focus solely on established directional trends.
HOW TO USE
Begin by defining the calculation scope in the settings, choosing either a fixed bar count or an anchored timeframe (e.g., Daily, Weekly). Select the appropriate scale (Linear or Logarithmic) to match your chart. Toggle the visibility of the central regression line and deviation bands (Upper, Lower, Optional, Highest, Lowest) as needed. In the "Signals" section, you can select a specific channel strategy and apply minimum thresholds for Pearson's correlation and the Theta angle. Enable the "Bands (Historical Plots)" option to visually audit the past states of the channel without current-bar distortion.
MECHANICS
At its core, the script utilizes the least-squares method to compute the slope and intercept of the price data. To keep the code modular and efficient, the architecture relies on several user-defined functions (e.g., f_calc_dynamic for historical rolling arrays, f_calc_slope_current for real-time line states, and f_scale_converter for logarithmic adjustments).
SIGNALS & EXECUTION LOGIC
It is important to note that the signal structure built here is a highly subjective approach to linear regression trading. In this sense, the current methodology is merely a "search for an answer" rather than a definitive solution. It aims to provide users with as flexible and customizable a workspace as possible.
Filters:
This indicator utilizes a state-machine (dir) to prevent consecutive redundant signals and to manage immediate directional reversals. All entry conditions can be independently gated by two optional mathematical filters: Pearson's R (minimum correlation strength) and Theta (θ) (minimum slope angle).
Channel Strategies:
The script features 5 distinct channel strategy options with specific entry and exit conditions:
1. None (Pure Trend)
• Logic: Ignores channel bands entirely and relies purely on trend momentum.
• Entry: Triggered when the mathematical Theta (θ) angle crosses the user-defined threshold
• Exit: Triggered when the Theta angle crosses the 0 line, indicating a trend exhaustion or directional shift.
2. Deviation | Break-Out
• Logic: Uses the current, dynamically calculated upper and lower standard deviation bands to catch momentum breakouts.
• Entry: Triggered when the close price crosses over the upper band (Long) or under the lower band (Short).
• Exit (Fakeout Protection): Triggered when the close price crosses back inside the respective entry band. This acts as a trailing stop to cut losses early during false breakouts.
3. Deviation | Mean Reversion
• Logic: Uses the current dynamic deviation bands to anticipate a price rebound towards the mean.
• Entry: Triggered when the close price crosses over the lower band (Long) or under the upper band (Short). Upon entry, a volatility-adjusted hard stop is dynamically recorded (Entry Band ± 1 Standard Deviation).
• Exit: Triggers either as a Take-Profit when the price wick (high for Longs, low for Shorts) hits the central Regression Line, OR as a Stop-Loss if the price breaches the recorded hard stop to prevent infinite drawdowns.
4. Highest & Lowest | Break-Out
• Logic: Uses 1-bar delayed ( ) highest and lowest recorded deviation lines to provide stable, non-repainting levels for breakout confirmation.
• Entry: Triggered when the close price crosses over the historical highest line (Long) or under the historical lowest line (Short).
• Exit (Fakeout Protection): Triggered when the close price crosses back inside the respective entry line.
5. Highest & Lowest | Mean Reversion
• Logic: Uses the stable 1-bar delayed highest and lowest lines to trade rebounds.
• Entry: Triggered when the close price crosses over the lowest line (Long) or under the highest line (Short). Similar to Option 3, a hard stop is recorded at the exact moment of entry.
• Exit: Triggers as a Take-Profit upon a wick touch to the central Regression Line, OR as a Stop-Loss upon breaching the recorded hard stop.
DISCLAIMER
This indicator is strictly a statistical observation tool, not a predictive financial model. Linear regression mathematically describes past price action; it does not forecast future movements. The mathematical filters and deviation bands provided are subjective interpretations of market data and should only be used as supplementary components within a broader, independent risk management framework. Indicator

Anchored Clusters Volume Profile [LuxAlgo]The Anchored Clusters Volume Profile indicator utilizes K-Means clustering to categorize historical price action into distinct groups within a user-defined range and generates individual volume profiles for each detected cluster. This tool provides a unique perspective on volume distribution by isolating price behaviors based on proximity rather than strictly chronological order.
🔶 USAGE
The indicator identifies "clusters" of price activity within a selected range defined by a starting and ending date. Each cluster is assigned a unique color and its own horizontal volume profile, allowing traders to see where liquidity is most concentrated within specific price regimes.
🔹 Identifying Institutional Zones
Traders can use the Point of Control (POC) of high-volume clusters to identify significant institutional interest. Because the K-Means algorithm groups price action by density rather than time, a cluster's POC often represents a "fair value" level where significant exchange occurred. These dashed POC lines frequently act as robust support or resistance levels when price returns to them in the future.
🔹 Market Regime Detection
By observing the vertical distribution and overlap of clusters, traders can identify market phases. Overlapping clusters with high volume often indicate accumulation or distribution phases (sideways markets), whereas distinct, vertically separated clusters with lower volume gaps between them suggest a trending environment. A shift from multiple overlapping clusters to a new, isolated cluster can signal a breakout or the start of a new trend.
🔹 Precision Entry & Exits
Cluster boundaries and POC lines provide concrete levels for trade management. An entry can be sought when price retests a high-volume cluster POC, while stops can be placed outside the total price range of that specific cluster (the area covered by its volume profile). Conversely, targets can be set at the POC of the next major cluster above or below current price action.
🔹 Volume Conviction
The tool provides specific volume metrics that allow traders to gauge conviction. By comparing the "Total" volume label of one cluster against another, a trader can determine which price regime had more participation. A breakout into a price zone with a high-volume cluster suggests stronger conviction and a higher probability of the level holding compared to a zone with low total volume.
🔶 DETAILS
Unlike traditional anchored volume profiles that provide a single histogram, this script employs a K-Means clustering algorithm to segment the range. This process involves:
Identifying the specific range of bars between the user-selected Start Time and End Time .
Initializing "centroids" across the price range of that period.
Iteratively assigning each price bar to the nearest centroid based on the HLC2 (median) price.
Recalculating centroids based on the volume-weighted average price of the assigned bars.
Finalizing assignments after the specified number of iterations to ensure stable clusters.
By separating price action into these clusters, the tool helps identify high-interest zones that might be obscured by a single, traditional Volume Profile.
🔶 SETTINGS
🔹 Anchor Settings
Start Time / End Time : Sets the beginning and end of the analysis range. These use the "Confirm" feature, allowing you to select the range directly on the chart after adding the indicator or changing settings.
Range Highlight : Adjusts the color and transparency of the background shading that identifies the analyzed range.
🔹 Clustering Settings
Number of Clusters : Sets how many distinct price groups the algorithm should attempt to find (2 to 10).
K-Means Iterations : Controls the number of times the algorithm refines the cluster centers. Higher values can lead to more stable results.
🔹 Volume Profile Settings
Rows per Cluster VP : Defines the vertical resolution (number of bins) for each individual cluster's profile.
Max VP Width (Bars) : Sets the maximum horizontal length of the volume profile histograms.
VP Offset : Adjusts the horizontal spacing between the current bar and the start of the volume profiles.
Highlight Price Dots : Toggles the visibility of the colored dots on the price action to identify cluster assignments.
Dot Size : Adjusts the size of the cluster assignment dots on the chart, ranging from tiny to huge.
Indicator

Indicator

Piano Frequency LevelsPiano Frequency Levels
This indicator applies the mathematical principles of musical harmony to market analysis, creating support and resistance levels based on authentic piano frequency ratios. Drawing from centuries-old musical theory, it maps the precise mathematical relationships between piano keys to price levels.
How It Works: The indicator uses the exact frequency ratios from equal temperament tuning - the same mathematical system that makes pianos sound harmonious. Each level represents an actual piano key frequency, scaled proportionally to your chosen anchor price.
Key Features:
• Piano-Based Ratios: Uses authentic 12-tone equal temperament frequency relationships (1.05946 ratio between semitones)
• Directional Intelligence: Automatically creates ascending levels from lows (resistance) or descending levels from highs (support)
• Musical Note Labels: Optional display of actual piano key names (C4, D#5, F6, etc.) alongside price levels
• Black Key Subdivisions: Toggle authentic sharp/flat keys between natural notes for additional precision
• Octave Color Coding: Each musical octave displays in a different color for easy visual identification
• Anchor Reference: Bright green line clearly marks your C-note reference point
Musical Foundation: Every level corresponds to an actual piano key. The anchor point represents "C" (the musical root), with levels progressing through the natural musical sequence: C, D, E, F, G, A, B, then repeating in higher octaves. This creates proportional spacing that mirrors the harmonic relationships musicians have used for centuries.
Usage:
1. Set your anchor to a significant market high or low
2. Choose your desired number of levels (typically 12-24 for 1-2 octaves)
3. Enable "Add Black Keys" for additional intermediate levels
4. Enable "Show Note Names" to see which piano key each level represents
The Theory: Musical harmony is based on precise mathematical ratios that create pleasing relationships between frequencies. These same mathematical principles may manifest in market movements, as price action often exhibits proportional relationships similar to musical intervals.
Unique Advantages:
• Based on established mathematical principles rather than arbitrary ratios
• Provides both major levels (white keys) and intermediate levels (black keys)
• Automatically adapts direction based on anchor type (high vs low)
• Maintains authentic musical relationships across all timeframes and price ranges
Important Note: This indicator presents a theoretical framework for market analysis. Like all technical analysis tools, it should be used in conjunction with other forms of analysis and proper risk management. The musical ratios provide a unique perspective on potential support and resistance levels, but past performance does not guarantee future results.
Transform your charts into a musical instrument and discover the hidden harmonies in market movements.
Indicator

Multi-AVWAP - Anchored - Gold -V1This script uses multi-day anchored VWAP.
What it does
This study plots multiple Anchored VWAP (AVWAP) lines from recent session starts (1, 2, 3, 4, 5, 10, 15, 20, 30, 90).
from the anchor forward. Each line shows a live label with the line’s current value and the current price for quick distance checks.
Best practices
Use on intraday timeframes for session-anchored lines.
Ensure the chart has enough history loaded for the longest lookback (e.g., 90 days).
For crypto or 24×7 markets, set session to a 24h window (e.g., 0000-2359) and turn off the exclude-ETH toggle if you want full-time anchoring.
Limitations
Different exchanges/markets use different RTH windows—pick the one that matches your venue.
Corporate actions/volume adjustments can make small discrepancies across platforms.
If no RTH exists on the exact calendar day (holidays), the 90d line anchors to the most recent available RTH open before that date. Indicator

NY Anchored VWAP and Auto SMANY Anchored VWAP and Auto SMA
This script is a versatile trading indicator for the TradingView platform that combines two powerful components: a New York-anchored Volume-Weighted Average Price (VWAP) and a dynamic Simple Moving Average (SMA). Designed for traders who utilize VWAP for intraday trend analysis, this tool provides a clear visual representation of average price and volatility-adjusted moving averages, generating automated alerts for key crossover signals.
Indicator Components
1. NY Anchored VWAP
The VWAP is a crucial tool that represents the average price of a security adjusted for volume. This version is "anchored" to the start of the New York trading session, resetting at the beginning of each new session. This provides a clean, session-specific anchor point to gauge market sentiment and trend. The VWAP line changes color to reflect its slope:
Green: When the VWAP is trending upwards, indicating a bullish bias.
Red: When the VWAP is trending downwards, indicating a bearish bias.
2. Auto SMA
The Auto SMA is a moving average with a unique twist: its lookback period is not fixed. Instead, it dynamically adjusts based on market volatility. The script measures volatility using the Average True Range (ATR) and a Z-Score calculation.
When volatility is expanding, the SMA's length shortens, making it more sensitive to recent price changes.
When volatility is contracting, the SMA's length lengthens, smoothing out the price action to filter out noise.
This adaptive approach allows the SMA to react appropriately to different market conditions.
Suggested Trading Strategy
This indicator is particularly effective when used on a one-minute chart for identifying high-probability trade entries. The core of the strategy is to trade the crossover between the VWAP and the Auto SMA, with confirmation from a candle close.
The strategy works best when the entry signal aligns with the overall bias of the higher timeframe market structure. For example, if the daily or 4-hour chart is in an uptrend, you would look for bullish signals on the one-minute chart.
Bullish Entry Signal: A potential entry is signaled when the VWAP crosses above the Auto SMA, and is confirmed when the one-minute candle closes above both the VWAP and the SMA. This indicates a potential continuation of the bullish momentum.
Bearish Entry Signal: A potential entry is signaled when the VWAP crosses below the Auto SMA, and is confirmed when the one-minute candle closes below both the VWAP and the SMA. This indicates a potential continuation of the bearish momentum.
The built-in alerts for these crossovers allow you to receive notifications without having to constantly monitor the charts, ensuring you don't miss a potential setup. Indicator

Volume Weighted Average Price Dynamic Slope [sgbpulse]VWAP Dynamic Slope: A Comprehensive Indicator for Trend Identification and Smart Trading
Introducing VWAP Dynamic Slope, an innovative TradingView indicator that harnesses the power of Volume Weighted Average Price (VWAP) and enhances it with immediate visual feedback. The indicator colors the VWAP line based on its slope, allowing you to quickly and easily identify the direction and strength of the current trend for the asset, providing advanced tools for in-depth analysis.
What is VWAP and Why is it so Important?
VWAP (Volume Weighted Average Price) is an indicator that represents the average price at which an asset has traded, weighted by the volume traded at each price level. Unlike a simple moving average, VWAP gives greater weight to trades executed with high volume, making it a reliable measure of the asset's "true" or "fair" price within a given period. Many institutional traders use VWAP as a central reference point for evaluating the effectiveness of entries and exits. An asset trading above its VWAP is considered to have bullish momentum, and below it – bearish momentum.
How it Works: Dynamic VWAP Slope Analysis
VWAP Dynamic Slope analyzes the inclination of the VWAP line and displays it using an intuitive color scheme:
Positive Slope (Uptrend): When the VWAP points upwards, signaling positive momentum, the default color will be green.
Negative Slope (Downtrend): When the VWAP points downwards, signaling negative momentum, the default color will be orange.
Trend Change (CHG): When a change in the VWAP's trend direction occurs, a "CHG" label will be displayed. The label's color will be green if the change is to an uptrend, and orange if the change is to a downtrend.
Identifying Steep Slopes for Increased Momentum:
The indicator's uniqueness lies in its ability to identify "steep" slopes – rapid and particularly strong changes in the VWAP's direction. This indicates exceptionally strong momentum:
Steep Positive Slope: The VWAP color will change to dark green, indicating significant buying pressure.
Steep Negative Slope: The VWAP color will change to dark red, indicating significant selling pressure.
Dynamic Momentum Strength Label: In situations of steep slope (positive or negative), a dynamic label will be displayed with the change value of the VWAP at that point. This label allows you to monitor momentum strength, intensification, or weakening in real-time.
Advanced Analytical Tools for Complete Control
VWAP Dynamic Slope provides you with unprecedented flexibility through a variety of customizable tools:
Multiple VWAP Anchors and Visual Marking:
Common Time Anchors: Choose whether the VWAP resets at the beginning of each Session (daily), Week, Month, Quarter, Year, Decade, or Century.
Advanced Intraday Anchors: Within the Session, you can choose to calculate VWAP specifically for Pre-Market, Regular Hours, and Post-Market hours. This option is particularly crucial for intraday traders.
Important Event Anchors: The indicator allows for VWAP resets at significant milestones such as Earnings, Dividends, and Splits, for analyzing the market's immediate reaction.
Visual Anchor Marking: To enhance clarity and orientation, a Label ⚓ can be displayed at each selected anchor point, helping to immediately identify the start point of the VWAP calculation in the chosen context.
Customizable Bands (Up to Three on Each Side):
Add up to three Bands above and below the VWAP to identify areas of deviation and excursion from the average price. You have two calculation options:
Standard Deviation: Based on volatility and statistical distance from the VWAP.
Percentage: Defines fixed percentage-based bands from the VWAP.
Key Pre-Market Levels (Pre-Market High/Low):
Display the Pre-Market High and Low levels as separate lines on the chart. These lines often serve as important psychological support and resistance zones, allowing you to see how the VWAP behaves near them.
Full Customization and Precise Control:
VWAP Source Selection: Determine which price data type will be used for the VWAP calculation. The default is HLC3 (average of High, Low, and Close), but any other relevant data source available in TradingView can be selected.
Offset: Set an offset for the VWAP line, allowing you to shift it left or right on the time axis by a chosen number of bars.
Customizable Colors: Choose your preferred colors for each slope state, Pre-Market High/Low lines, and Bands.
Setting the "Steepness" Threshold (Per-mille Price Change Per Minute ‱/min with Auto-Adjustment): Determine the sensitivity for identifying a steep slope by setting the required change threshold in VWAP in terms of per-mille price change per minute (‱/min). The indicator performs smart adjustment for any timeframe you select on the chart (e.g., 30 seconds, 1 minute, 5 minutes, 10 minutes, etc.), ensuring that the "steepness" setting maintains consistency and relevance.
Examples for Setting the Steepness Threshold:
Suppose you set the steepness threshold to 0.3‱/min (per-mille price change per minute).
On a 30-second chart: The indicator will check if the VWAP changed by 0.15 ‱/min (half of the per-minute threshold) within a single bar. If so, the slope will be considered steep. Explanation: Since 30 seconds is half a minute, the indicator looks for a change that is half of the threshold set for a full minute.
On a 1-minute chart: The indicator will check if the VWAP changed by 0.3 ‱/min (the full per-minute threshold) within a single bar. If so, the slope will be considered steep. Explanation: Here, the bar represents a full minute, so we check the full threshold.
On a 5-minute chart: The indicator will check if the VWAP changed by 1.5 ‱/min (5 times the per-minute threshold) within a single bar. If so, the slope will be considered steep. Explanation: A 5-minute bar contains 5 minutes, so the cumulative change in VWAP needs to be 5 times greater to be considered "steep" on the same scale.
In summary, this setting allows you to precisely and uniformly control the sensitivity of steep slope detection across all timeframes, providing immense flexibility in analyzing the asset's momentum.
Advantages of Using Per-mille Price Change Per Minute (‱/min)
Using per-mille price change per minute (‱/min) offers several key advantages for your indicator:
Normalized and Objective Measurement: It provides a uniform scale for the VWAP's rate of change, regardless of the asset's price or nominal value. A 0.1 per-mille change per minute always carries the same relative significance.
Comparison Across Different Asset Prices: Using per-mille allows for direct comparison of VWAP movement strength between assets trading at very different prices (e.g., a $100 asset versus a $1 asset), enabling an understanding of true momentum without bias from the nominal price.
Smart Timeframe Agnostic Adjustment: This is a critical capability. The indicator automatically adjusts the per-mille per minute threshold you set to any chart timeframe (30 seconds, 1 minute, 5 minutes, etc.), maintaining consistency in "steepness" detection without manual recalibration.
Precise Momentum Identification: This measurement precisely identifies when the VWAP's rate of change becomes significant, and when momentum strengthens or weakens, contributing to more informed trading decisions.
In short, per-mille change per minute (‱/min) provides accuracy, consistency, and flexibility in identifying VWAP momentum changes, with smart adaptation across all timeframes.
Who is this Indicator For?
VWAP Dynamic Slope is a powerful tool for:
Intraday Traders: For quick identification of intraday trend directions and momentum across any timeframe, with specific consideration for Pre-Market, Regular Hours, or Post-Market VWAP, and incorporating key pre-market levels.
Swing Traders and Long-Term Investors: For analyzing longer-term trends based on periodic and event-driven VWAP anchors.
Beginner Traders: As an excellent visual aid for understanding the relationship between price, volume, and trend direction, and how different anchor points, pre-market levels, and data sources influence price behavior.
Experienced Traders: For integration with existing strategies, gaining additional confirmation for trend strength identification, and highly precise and flexible parameter calibration.
VWAP Dynamic Slope provides a rich, multi-dimensional layer of information about the VWAP, helping you make more informed trading decisions in real-time, within the context of your chosen asset.
Indicator