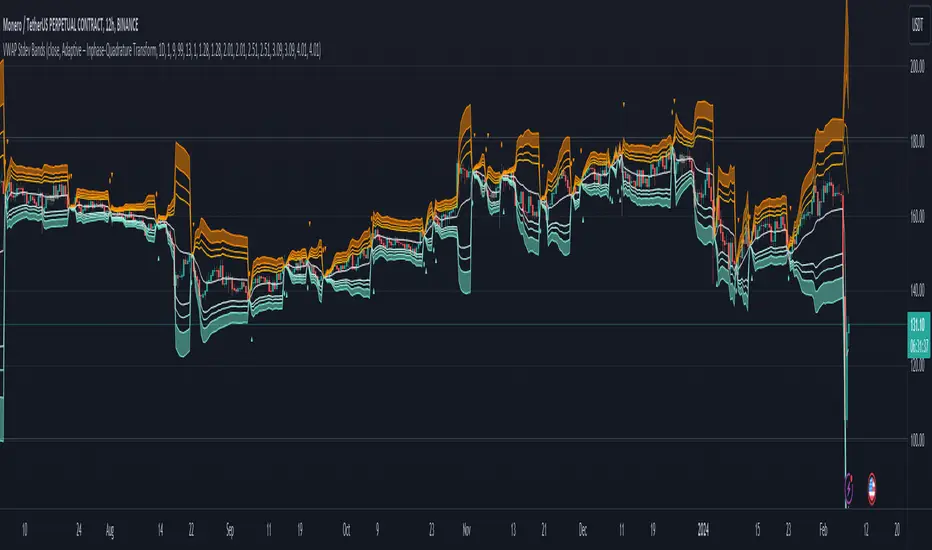
Tactical DeviationThis indicator is a mean-reversion system grounded in statistical deviation from the Volume Weighted Average Price (VWAP). Unlike standard Bollinger Bands or static envelopes, the "Tactical Deviation" script integrates Multi-Timeframe Analysis, Dynamic Volatility Scaling, and Market Structure Validation to identify high-probability exhaustion points.
Underlying Concepts & Methodology
The core philosophy of this script is that price tends to revert to its volume-weighted mean after reaching sta
Indicator